Residential Property Investment Gurgaon 2025 Guide
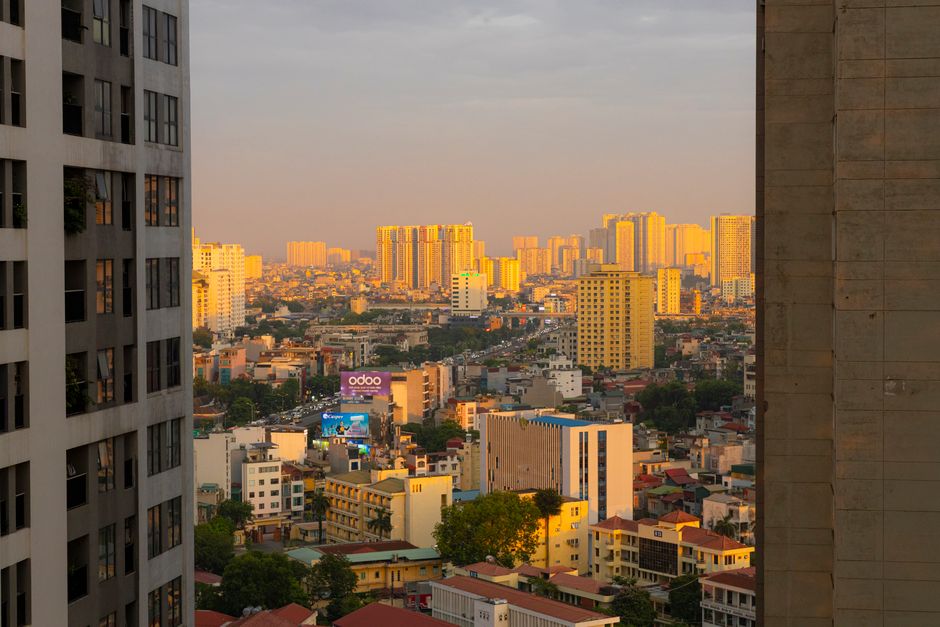
Gurgaon’s skyline has never looked more contested — cranes in Dwarka Expressway corridors, luxury towers rising along Golf Course Extension, and mid-segment projects quietly filling the gaps along Southern Peripheral Road. For anyone evaluating residential property investment Gurgaon today, the city is not a single market; it is a collection of micro-markets with genuinely different risk-reward profiles.
Understanding where you are on the capital appreciation vs. rental income spectrum matters more in 2025 than it did even three years ago, because interest rates, remote-work patterns, and new infrastructure have reshuffled the rankings considerably.
Micro-Markets That Are Delivering Capital Appreciation
Capital appreciation is strongest where supply is constrained and infrastructure is actively improving. Three zones stand out this year.
Dwarka Expressway corridor has arguably been Gurgaon’s most rewarding bet over the last 24 months. With the expressway now fully operational and the extension of the Delhi Metro’s Green Line progressing, properties in Sectors 84–95 have recorded price increases of 28–35% since early 2023, according to data tracked by ANAROCK Property Consultants, one of India’s most-cited residential research firms. Inventory launched here is being absorbed faster than it is replaced, which is textbook appreciation territory.
Golf Course Extension Road (New Gurugram, Sectors 57–65) remains the city’s luxury-appreciation story. Branded residences, ultra-premium plotted developments, and gated communities targeting C-suite buyers have pushed average ticket sizes past ₹4 crore. Because land parcels are scarce and DDJAY (Deen Dayal Jan Awas Yojana) plotted schemes have matured, resale premiums here are compounding well above inflation.
Southern Peripheral Road (SPR), particularly Sectors 68–75, is the sleeper pick. Commercial office parks by major IT occupiers are pulling in talent that, in turn, needs upscale housing within a 15-minute commute. Price per square foot has climbed roughly 18–22% year-on-year, yet SPR still trades at a discount to Golf Course Extension, leaving room for further appreciation as the precinct matures.
If capital growth is your priority, the common thread across all three zones is proximity to either metro connectivity or established employment hubs — ideally both.
Micro-Markets That Are Delivering Rental Income
Rental yield in Gurgaon has historically been modest (2.5–3.5%) compared to cities like Pune or Hyderabad, but specific pockets are now pushing that ceiling upward.
Cyber City and DLF Phase 1–5 continue to command the city’s most dependable rental demand. Multinational tenants, expatriate families, and senior corporate professionals rent here on long leases with low vacancy periods. A well-maintained 3BHK in DLF Phase 3 can yield ₹65,000–₹90,000 per month, translating to gross yields of 3.2–3.8%. Churn is low, which matters as much as the headline number.
Sohna Road (Sectors 47–50) has become a sweet spot for mid-segment rental investors. The concentration of co-working spaces and the presence of companies like Google and American Express in nearby sectors have created steady demand from young professionals who prefer renting over buying. Typical 2BHK rents have risen 14% year-on-year, and supply pipelines remain manageable enough that vacancy has not spiked.
Manesar and IMT Manesar, often overlooked by retail investors, is a manufacturing and logistics hub drawing workers from across Haryana. Rental demand here is volume-driven rather than premium-driven, but gross yields of 4–4.5% are among the highest in the Gurgaon metropolitan region. The trade-off is that capital appreciation is slower and tenant profiles are more transient.
For rental-income seekers, CREDAI’s market outlook reports provide useful benchmarks on occupancy trends and projected supply pipelines across Haryana’s key cities, including Gurgaon.
How to Decide Which Strategy Fits You
The honest answer is that most investors in 2025 are not choosing one or the other — they are stress-testing both scenarios before committing. A few practical filters:
– Holding period: If you can hold for seven-plus years, appreciation-focused zones like Dwarka Expressway make sense even if early yields are thin (often 1.8–2.2%). If you need income within 12–18 months of possession, Sohna Road or Cyber City adjacencies are safer bets.
– Ticket size: Golf Course Extension luxury plays require deep pockets and a patient exit strategy. Sohna Road and SPR offer entry points in the ₹80 lakh–₹1.5 crore range that are accessible to a wider investor base.
– RERA compliance: Always verify project registration on the Haryana RERA portal before signing anything. Delayed possession remains the single biggest destroyer of both yield and IRR in Gurgaon.
Frequently Asked Questions
Which area in Gurgaon is best for residential property investment in 2025?
There is no single best area — it depends on your goal. For capital appreciation, Dwarka Expressway and Golf Course Extension Road are leading picks. For rental income, DLF Phase 1–5 and Sohna Road offer more consistent returns with lower vacancy risk.
What rental yield can I realistically expect in Gurgaon?
Gross rental yields across most of Gurgaon sit between 2.5% and 3.8%. Manesar and IMT Manesar can push toward 4–4.5%, while luxury segments in Golf Course Extension typically yield 2–2.5% gross despite strong capital gains.
Is Dwarka Expressway a good investment in 2025?
For capital appreciation, yes. Infrastructure completion and metro connectivity have significantly reduced the risk premium that once made buyers cautious. However, rental demand is still building, so investors focused purely on yield may need to wait 2–3 more years for the precinct to fully mature.
How do I verify a project before investing in Gurgaon?
Check the project’s RERA registration number on the Haryana RERA portal, confirm the developer’s past delivery track record, and independently verify OC (Occupancy Certificate) status for completed projects. Avoid off-plan investments where land title disputes are unresolved.
Are property prices in Gurgaon likely to correct in 2025?
A broad correction appears unlikely given the demand-supply dynamics. However, over-leveraged mid-segment launches in peripheral sectors with weak social infrastructure could see price stagnation if employment growth slows. Micro-market selection, rather than a city-wide call, is the more reliable analytical frame.
What is the minimum budget needed for residential property investment in Gurgaon?
Useful entry points begin around ₹50–60 lakh for studio and compact 1BHK units in Sohna Road or Manesar. Mid-segment 2BHK investments in established sectors like 47–57 typically require ₹80 lakh–₹1.2 crore. Premium and luxury segments start at ₹2.5 crore and above.
Trusted Property Consultants Gurgaon: Vet Before You Invest
Handing your life savings to someone you met at a property expo or found through a friend-of-a-friend referral is, frankly, a leap of faith most of us cannot afford to get wrong. Gurgaon’s real estate market moves fast, prices are high, and the consultant standing between you and a good deal has an enormous amount of power. That is precisely why knowing how to identify trusted property consultants Gurgaon buyers and investors actually rely on — rather than those who simply talk a good game — is non-negotiable before you sign anything.
This guide walks you through the concrete steps to vet a property consultant, the warning signs that should make you walk away, and the positive signals that tell you you are in capable hands.
Red Flags That Should Stop You Cold
They cannot show you a RERA registration number.
Under the Real Estate (Regulation and Development) Act, 2016, any agent facilitating property transactions in India must be registered with the relevant state’s Real Estate Regulatory Authority. In Haryana, that means Haryana RERA. If a consultant hesitates, deflects, or offers excuses when you ask for their registration number, treat it as a dealbreaker — full stop.
They push urgency without substance.
Phrases like “this price is only valid today” or “three other buyers are ready” may occasionally reflect reality, but they are also classic pressure tactics used to short-circuit your due diligence. A genuine consultant will give you time to review documents, consult a lawyer, and think clearly.
Their fee structure is murky.
Legitimate consultants earn a commission, typically from the developer or seller, and they should be upfront about this. If someone is vague about how they get paid, or if they are asking for large upfront fees before any service has been delivered, that opacity is a problem.
They discourage independent legal checks.
No credible professional will tell you that hiring a property lawyer to review title documents is unnecessary or a waste of money. Any consultant who steers you away from independent verification has a reason to do so, and that reason is rarely in your favour.
Their track record is verbal-only.
Testimonials they quote verbally are easy to fabricate. Ask for written references, Google reviews tied to real names, or LinkedIn profiles of past clients willing to speak with you. If the only evidence of their success comes from their own mouth, that should give you pause.
They are unfamiliar with the micro-market.
Gurgaon is not one market — it is dozens. Sector 29 behaves differently from Dwarka Expressway or Golf Course Extension Road. A consultant who cannot speak fluently about recent transaction prices, upcoming infrastructure changes, or developer reputations in your target area is simply not equipped to advise you.
Green Lights That Signal You Can Move Forward
RERA registration is verifiable and current.
A consultant who proactively shares their RERA number and encourages you to verify it online is starting the relationship with transparency. This is table stakes — the floor, not the ceiling — but it immediately narrows the field.
They ask more questions than they answer.
The best trusted property consultants Gurgaon professionals recommend are the ones who spend the first meeting understanding your needs: your investment horizon, your risk appetite, whether you need rental yield or long-term appreciation, and what your financing situation looks like. A consultant pitching projects before they understand you is selling, not advising.
They offer comparative options and honest trade-offs.
A good consultant will show you three or four options and walk you through the genuine pros and cons of each — including the one that earns them a lower commission. If every option they present happens to be from the same developer, ask why.
They connect you with independent professionals.
A consultant worth trusting will have a network that includes property lawyers, chartered accountants familiar with real estate taxation, and home loan advisors — and they will actively encourage you to use them. According to CREDAI, India’s apex body for real estate developers, buyer awareness and professional advisory are central pillars of a healthy property transaction ecosystem.
Their communication is consistent and documented.
They follow up calls with written summaries, send you documents promptly, and do not disappear after you show interest. Responsiveness before you commit is a reliable indicator of how they will behave after.
They have local longevity.
Someone who has operated in Gurgaon’s property market for five or more years has survived market cycles, regulatory changes, and shifting developer fortunes. That experience is genuinely valuable and hard to fake.
Frequently Asked Questions
How do I verify a property consultant’s RERA registration in Haryana?
Visit the Haryana RERA portal and search for the agent using their name or registration number. All registered agents are listed publicly, and you can confirm whether their registration is active or lapsed.
What is a reasonable commission for a property consultant in Gurgaon?
Most consultants earn between 1% and 2% of the transaction value, paid by the developer or seller rather than the buyer. If a consultant is asking you — the buyer — to pay a significant upfront fee, request a detailed written breakdown before agreeing to anything.
Should I use one consultant or speak to several?
Speaking to two or three consultants before committing is sensible. It gives you a reference point for market knowledge, communication style, and the range of options available. Just be transparent with each one that you are still in the evaluation phase.
Is a consultant with a big agency always safer than an independent one?
Not necessarily. Brand recognition provides some accountability, but individual conduct matters more. Evaluate the specific person you will be working with — their experience, their references, and how they communicate — not just the logo on their business card.
What documents should a consultant help me review before purchase?
At minimum: the title deed, encumbrance certificate, building approvals, RERA project registration, and the draft sale agreement. A trustworthy consultant will walk you through each one and recommend a lawyer for final verification.
Can a consultant represent both buyer and seller in the same deal?
Technically yes, but this creates a conflict of interest. If your consultant is also working for the developer or seller, ask how they will ensure your interests are protected. A written disclosure of all parties they represent is a reasonable thing to request.
Real Estate Advisory Services: Why You Need One
Buying property feels straightforward until it isn’t. The listing looks perfect, the open house goes smoothly, and then — somewhere between the offer, the inspection, and the closing table — things get complicated fast. That’s the moment most buyers wish they had invested in professional real estate advisory services from the start.
An advisor isn’t the same as a traditional buyer’s agent who simply shows you homes and submits paperwork. A real estate advisor takes a consultative approach: they analyze your financial situation, assess market conditions, stress-test your assumptions, and help you make a decision that holds up years after moving day.
What a Real Estate Advisor Actually Does
The day-to-day work of a real estate advisor covers far more ground than most buyers expect.
Market analysis and pricing strategy. Advisors don’t just pull comparable sales — they interpret them. They’ll tell you why a house priced at $650,000 in a softening market is likely to close at $620,000, and they’ll back that with data rather than gut feel. According to the National Association of Realtors, buyers who work with knowledgeable professionals consistently report higher satisfaction with their purchase price outcomes.
Due diligence coordination. A good advisor orchestrates the inspection process, flags red flags before you’re legally committed, and knows which issues are deal-breakers versus negotiating chips. They’re not just reading the inspection report — they’re reading between the lines.
Contract and negotiation expertise. Purchase agreements are dense documents. An advisor reviews contingency language, earnest money terms, and seller concession structures to protect you. They’ll push back on clauses that look standard but quietly shift risk onto the buyer.
Network access. Established advisors bring a vetted network of lenders, inspectors, attorneys, and contractors. This isn’t a minor perk. A trusted inspector who catches a foundation issue saves you tens of thousands of dollars. A lender who closes on time saves your deal.
Long-term investment perspective. Rather than asking “do you like this house?” an advisor asks “will this house serve your goals in five, ten, or twenty years?” They factor in neighborhood trajectory, resale liquidity, and how the property fits your broader financial picture.
What Separates an Advisor from a Standard Agent
Traditional buyer’s agents earn a commission when a transaction closes. That structure, while common, creates an incentive to close deals rather than to scrutinize them. A real estate advisor — whether fee-based or commission-based — is positioned explicitly as your advocate, not a transaction facilitator. The distinction matters especially in competitive markets where speed pressure can override sound judgment.
Why Buying Without One Costs You More
The most common objection to hiring an advisor is cost. That concern deserves a direct answer: in most cases, buyers who skip professional real estate advisory services lose far more than they save.
Overpaying on purchase price. Without a skilled negotiator in your corner, sellers and their agents set the terms. Buyers routinely pay 2–5% above what a well-represented buyer would in the same transaction. On a $500,000 home, that’s $10,000–$25,000 left on the table.
Missed inspection issues. Unrepresented buyers often waive inspections to compete, or they don’t know which inspection findings warrant renegotiation. The Consumer Financial Protection Bureau notes that unexpected home repair costs are among the leading financial stressors for first-time buyers in the years following purchase.
Contract missteps. Poorly structured contingencies can leave a buyer unable to recover their earnest money if a deal falls through for legitimate reasons. An advisor knows how to write airtight contingencies that protect your deposit without making your offer look weak.
Emotional decision-making. Buying a home is personal. That’s not a flaw — it’s human. But emotion without a counterbalance leads to overbidding on homes you’ve fallen in love with, overlooking serious problems because the kitchen is beautiful, or panic-buying in a rising market without a clear-headed assessment of value. An advisor provides that counterbalance.
Post-purchase regret. Studies consistently show that buyers who felt rushed or under-advised are more likely to report dissatisfaction with their purchase. An advisor slows things down just enough to make sure you’re confident — not just committed.
The fee structure for real estate advisory services varies. Some advisors charge a flat fee, others work on commission, and some blend both. In many transactions, the seller covers the buyer’s advisor’s compensation through the sale proceeds, meaning the buyer receives professional guidance at no direct out-of-pocket cost. Even when there is a direct fee, the math almost always favors the investment.
Frequently Asked Questions
What is the difference between a real estate advisor and a buyer’s agent?
A buyer’s agent primarily helps you find and purchase a property, earning a commission at closing. A real estate advisor takes a broader consultative role — analyzing your financial goals, scrutinizing deals critically, and advocating for your long-term interests rather than simply facilitating a transaction.
How much do real estate advisory services typically cost?
Costs vary widely. Some advisors charge flat project fees ranging from a few hundred to several thousand dollars. Others work on commission, which in many markets is paid by the seller. Always clarify the fee structure upfront so there are no surprises at closing.
Is a real estate advisor worth it for a straightforward purchase?
Yes — straightforward purchases can become complicated quickly. Even an uncomplicated transaction involves contract language, inspection findings, and financing contingencies that benefit from professional review. The risk of skipping guidance rarely justifies the savings.
When should I engage a real estate advisor in the buying process?
As early as possible — ideally before you start actively touring properties. An advisor shapes your search criteria, helps you understand true market value in your target area, and ensures your financing is structured correctly before you fall in love with a home.
Can a real estate advisor help with investment properties, not just primary homes?
Absolutely. Real estate advisory services are especially valuable for investment purchases, where return on investment, rental income projections, and exit strategy matter as much as the property itself.
What should I look for when choosing a real estate advisor?
Look for demonstrated local market knowledge, a clear explanation of how they’re compensated, verifiable client references, and a communication style that prioritizes your questions over their schedule. An advisor who listens carefully before speaking is almost always more valuable than one who talks fast.
How to Buy Property in India: 11 Due Diligence Steps

Purchasing real estate is one of the largest financial decisions most people ever make, and when you set out to learn how to buy property in India, the complexity can feel overwhelming. Opaque title records, fragmented local regulations, and high-pressure sales tactics are genuine hazards — not just urban legends. The good news is that a disciplined due diligence process dramatically reduces your risk. Work through every step below before handing over a rupee.
The Legal and Title Checks You Cannot Skip
1. Verify the title chain for at least 30 years.
Request all original sale deeds, gift deeds, or inheritance documents going back three decades. A clean, unbroken chain confirms the seller has the legal right to sell. Any gap is a red flag worth investigating with a property lawyer.
2. Get an encumbrance certificate (EC).
Obtain an EC from the sub-registrar’s office covering the same 30-year window. The EC lists every mortgage, lien, and charge registered against the property. If the seller claims there is no loan on the property but the EC says otherwise, walk away or insist on full loan closure before proceeding.
3. Confirm land-use and zoning classification.
Check the local development authority’s master plan to confirm the land is classified for the purpose you intend — residential, commercial, or agricultural conversion. Building a home on land zoned for agriculture can lead to demolition orders and zero compensation.
4. Inspect approved building plans.
For under-construction or already-built structures, ask for the approved building plan sanctioned by the municipal corporation or panchayat. Compare what is on paper with what is on the ground. Unauthorised floors or extensions may attract penalties or demolition.
5. Check RERA registration for new projects.
If you are buying from a developer, verify the project’s registration on your state’s Real Estate Regulatory Authority portal. RERA-registered projects are legally obligated to disclose timelines, approvals, and escrow accounts — giving you significant consumer protection that unregistered projects do not.
6. Review property tax receipts.
Ask for the last three to five years of paid property tax receipts. Unpaid dues become your liability the moment ownership transfers. Also confirm the name on the tax records matches the seller’s identity documents.
7. Confirm there are no pending litigation matters.
Have a lawyer run searches at the local civil court and the high court to check whether the property is party to any lawsuit, partition dispute, or insolvency proceedings. Litigation-encumbered properties can freeze your ownership rights for years.
Financial, Physical, and Procedural Checks
8. Conduct an independent market valuation.
Do not rely solely on the builder’s pricing or a broker’s word. Hire a certified valuer to assess fair market value independently. This protects you from overpaying and also determines the stamp duty baseline, as the government’s circle rate sets the minimum taxable value for registration.
9. Inspect the physical condition thoroughly.
For resale properties, hire a qualified structural engineer to check for dampness, foundation integrity, and electrical wiring quality. Cosmetic renovations often hide serious structural problems. The cost of a professional inspection — typically ₹5,000 to ₹15,000 — is trivial compared to repair bills.
10. Understand all costs before you commit.
The sticker price is never the final price. Budget for stamp duty (typically 5–7% of property value depending on the state), registration fees, GST on under-construction units, broker commissions, home loan processing fees, and society transfer charges. According to guidance published by the Reserve Bank of India, borrowers should also account for property insurance when planning home loan repayments.
11. Draft a robust sale agreement before paying any advance.
Before paying a token or booking amount, have a lawyer draft or review the sale agreement. It must specify the total consideration, payment schedule, possession date, penalty clauses for delay, and what happens if approvals are denied. Never rely on verbal assurances — what is not in the agreement does not exist legally.
Knowing how to buy property in India is ultimately about asking the right questions at each stage. Sellers and developers rarely volunteer uncomfortable information, so your due diligence process is your primary defence.
Take your time. A genuinely good property will still be available after a thorough two-to-four week verification period. If a seller insists you must decide within 24 hours, that urgency itself is a warning sign worth heeding.
Frequently Asked Questions
How long does the property buying process take in India?
From shortlisting to registration, expect the process to take between 60 and 120 days if no title disputes arise. Complex cases involving inherited property or NRI sellers can take longer due to additional documentation requirements.
Is it safe to buy under-construction property in India?
It can be, provided the project is RERA-registered and the developer has a track record of delivering on time. Always check that construction funds are held in an escrow account as mandated by RERA, which prevents diversion of buyer payments.
What is circle rate and why does it matter?
Circle rate (also called guidance value or ready reckoner rate) is the minimum property value set by state governments for stamp duty calculation. Even if you negotiate a lower purchase price, stamp duty is calculated on whichever is higher — the actual price or the circle rate.
Can an NRI buy property in India?
Resident Indians face no restrictions, and Non-Resident Indians (NRIs) can purchase residential and commercial property freely. However, NRIs cannot buy agricultural land, farmhouses, or plantation property without special RBI approval.
Do I need a lawyer or can I rely on the broker?
You should always engage an independent property lawyer. A broker’s income depends on the transaction closing; a lawyer’s duty is solely to your interests. Legal fees for a standard property transaction typically range from ₹10,000 to ₹30,000 — money well spent.
What happens if the seller has an outstanding home loan on the property?
The existing loan must be fully closed and the original documents retrieved from the lender before registration. One common approach is a tripartite agreement among the buyer, seller, and the lender, where part of the purchase price is paid directly to the bank to discharge the mortgage.
Residential Property Investment for Beginners: Step-by-Step
Buying your first investment property is one of the most significant financial decisions you will ever make. The gap between “I want to invest in property” and actually holding a set of keys can feel enormous — filled with mortgage jargon, competing advice, and the nagging fear of making an expensive mistake. The good news is that residential property investment for beginners becomes far less intimidating once you break it into a logical sequence of steps. This roadmap does exactly that.
Setting Your Budget and Financial Foundations
Before you browse a single listing, you need an honest picture of what you can actually afford — not what you hope you can afford.
Work out your borrowing capacity first. Speak to a mortgage broker or your bank to get an Agreement in Principle (AIP). Lenders assess investment mortgages differently from residential ones: they typically require a 20–25% deposit, and they stress-test rental income to ensure it covers 125–145% of the monthly mortgage payment. Knowing your ceiling early stops you falling in love with a property that was never within reach.
Build your full cost picture. Purchase price is just the headline number. Stack up stamp duty (or its local equivalent), legal fees, survey costs, letting agent fees, landlord insurance, and an emergency maintenance reserve. A common rule of thumb is to budget an additional 8–10% of the purchase price for these upfront costs. Running short at completion is a stressful and avoidable problem.
Define your return targets. Two metrics matter most at this stage: gross rental yield (annual rent divided by purchase price, expressed as a percentage) and cash flow (monthly rent minus all monthly outgoings). A gross yield below 4% in a high-cost city may still work if capital growth is your primary goal, but if you need the investment to pay for itself from day one, target 6% or higher. The UK Government’s guidance on property income tax is worth reading at this stage, because tax treatment directly affects your net return.
Stress-test every assumption. What happens if the property sits vacant for two months? What if interest rates rise by 1%? Investors who skip this exercise are often the ones who sell under pressure two years later.
Finding, Evaluating, and Securing the Right Property
With your finances organised, you can approach the market methodically rather than emotionally.
Choose your strategy before you choose a location. Are you targeting young professionals who want a low-maintenance city flat? Families who need good school catchment areas? Students near a university? Each tenant type has different priorities, and those priorities should dictate where you buy and what type of property you buy. Trying to find the perfect property without a strategy is like shopping without a list.
Research locations with data, not instinct. Look for areas where employment is growing, transport links are improving, or regeneration money is being spent. Rental demand in these areas tends to be more resilient, and void periods shorter. Check average asking rents on platforms like Rightmove’s rental market data to validate whether asking rents in a target area are realistic.
Carry out thorough due diligence on every shortlisted property. Commission a RICS-accredited surveyor rather than relying on the lender’s basic valuation. A HomeBuyer Report or full structural survey will surface issues — subsidence, damp, roof wear — that can turn a promising investment into a money pit. Paying £400–£800 for a survey is cheap insurance against a five-figure repair bill.
Understand the negotiation landscape. In a buyer’s market, 5–10% below asking price is often achievable, especially on properties that have been sitting unsold for more than eight weeks. In a competitive market, moving quickly with a clean offer (no chain, finance agreed) is often worth more than a slightly higher bid from a chain buyer.
Manage the legal process actively. Appoint a solicitor experienced in buy-to-let conveyancing. Chase your solicitor weekly rather than waiting for them to come to you — transactions that drift are transactions that fall through. Confirm the completion date in writing as early as possible, and have your deposit funds ready to transfer immediately when contracts exchange.
Prepare for tenancy before you complete. While conveyancing is underway, arrange landlord insurance, research local letting agents, and draft a compliance checklist covering gas safety certificates, electrical installation condition reports (EICRs), Energy Performance Certificates (EPCs), and deposit protection. Being operationally ready on completion day means your property can generate income within weeks, not months.
The journey from first viewing to key handover typically takes three to five months. Patience and preparation — not luck — are what separate investors who build long-term portfolios from those who treat residential property investment for beginners as a one-time gamble.
Frequently Asked Questions
How much deposit do I need for a residential investment property?
Most buy-to-let mortgage lenders require a minimum deposit of 20–25% of the property’s purchase price. A larger deposit — say 30–35% — typically unlocks better interest rates, which improves your monthly cash flow from day one.
Is a limited company better than buying in my personal name?
This depends heavily on your income tax band and longer-term portfolio plans. Higher-rate taxpayers often benefit from purchasing through a limited company because mortgage interest is fully deductible. However, company mortgages can carry higher rates and additional admin costs. Speak to a qualified accountant before making this decision.
How do I calculate rental yield on a property?
Divide the annual rental income by the property’s purchase price, then multiply by 100. For example, a property bought for £200,000 generating £10,000 per year in rent has a gross yield of 5%. Always calculate net yield too, subtracting running costs from the income figure before dividing.
What insurance do I need as a landlord?
At a minimum you need buildings insurance and landlord liability insurance. Contents insurance is advisable if the property is furnished. Some landlords also take out rent guarantee insurance, which covers lost rent if a tenant defaults — particularly useful during the early years of building your portfolio.
How long does the purchase process typically take?
From offer acceptance to completion, expect three to five months for a straightforward buy-to-let purchase. Complex chains, slow solicitors, or mortgage complications can extend this. Keeping communication flowing with your solicitor and mortgage broker is the single most effective way to stay on schedule.
Can I manage the property myself instead of using a letting agent?
Yes, but self-management requires time, local knowledge, and confidence handling legal compliance, maintenance calls, and occasionally difficult conversations with tenants. Full property management through an agent typically costs 10–15% of monthly rent but buys you peace of mind and removes day-to-day involvement, which many first-time investors find invaluable.
Luxury Apartments In Gurgaon: High-Yield Pre-Leased Strategy

Gurgaon’s residential real estate market has matured significantly over the last decade, and savvy investors are no longer content with simple capital appreciation. The new play is pre-leasing — securing a creditworthy tenant before or immediately after purchase, then positioning the property as a rent-generating asset that commands a premium valuation. If you own or are considering buying one of the many luxury apartments in Gurgaon, this guide walks you through a practical, repeatable strategy to make that transition.
Understanding the Pre-Leased Asset Model and Why It Works in Gurgaon
A pre-leased asset is a property that already has a signed lease agreement with an established tenant in place. In commercial real estate this is commonplace, but the concept is increasingly relevant for high-end residential units in demand corridors like Golf Course Road, DLF Cyber City, and Sector 54.
Why does this model work particularly well here? Gurgaon hosts the Indian headquarters of dozens of Fortune 500 companies. Senior executives, expatriate professionals, and C-suite relocations generate consistent demand for furnished, service-ready apartments with lease terms of two to five years. According to Knight Frank India’s residential research, luxury residential rentals in Gurugram’s prime micro-markets have seen rental yields climb closer to 4–5%, outpacing many other Indian metros for comparable asset classes.
The investor benefit is straightforward: when a unit carries a signed lease with a reputable corporate or institutional tenant, its market value increases because the buyer is acquiring an income stream, not just square footage. Banks and NBFCs also treat pre-leased residential assets more favourably for loan-against-property products, which improves your overall capital efficiency.
Choosing the Right Micro-Market and Project
Not every luxury project qualifies. Tenants paying premium rents expect proximity to commercial hubs, reliable infrastructure, and building-level amenities — concierge, high-speed elevators, backup power, and security. Projects in Golf Course Extension Road, Sohna Road’s upper segment, and sectors adjacent to NH-48 consistently attract corporate tenants. When evaluating a unit, verify the society’s maintenance quality, because institutional tenants will walk away from buildings with poor upkeep regardless of the apartment’s interior condition.
Preparing the Unit for Corporate-Grade Tenancy
Furnishing strategy is where many landlords leave money on the table. Corporate tenants prefer fully furnished or semi-furnished units with neutral palettes, ergonomic workspaces, and reliable internet infrastructure. A targeted spend of ₹15–25 lakhs on quality furniture, smart home integration, and kitchen appliances can lift achievable monthly rent by 25–35%. Commission a professional interior fit-out — not a rushed, budget job — because the photography and virtual tour you create from a well-staged unit directly determines the quality of tenant inquiries you attract.
The Step-by-Step Process to Pre-Lease Your Luxury Apartment
Step 1 — Legal and Documentation Readiness
Before approaching any tenant or leasing agent, ensure your title documents, occupation certificate, and society NOC are clean and accessible. Corporate HR teams and relocation agencies require these upfront. Gaps at this stage can disqualify your property from a shortlist instantly.
Step 2 — Engage a Specialist Leasing Agent
Generalist brokers rarely have access to the corporate relocation desk. Identify firms that specifically handle executive housing in Gurgaon and work on retainer or co-broking models. Brief them with a professional property sheet that includes floor plan, amenity list, proximity to business districts, and rental expectations.
Step 3 — Price It to the Market, Not to Your Aspirations
Check comparable lease transactions — not listings — in your building and immediate vicinity over the last six months. Overpricing by even 10–15% can leave a unit vacant for months, which erodes yield more than a slightly lower rent on a signed two-year lease would.
Step 4 — Structure the Lease Professionally
Work with a property lawyer to draft a Leave and Licence Agreement or a registered lease deed depending on the tenure. Include a rent escalation clause (typically 5–10% annually), a security deposit of two to three months’ rent, and clear maintenance responsibility terms. A well-drafted agreement protects your yield and makes the asset more attractive to any future buyer who inherits the lease.
Step 5 — Certify the Asset for Resale or Refinancing
Once the lease is signed, you hold a pre-leased asset. At this point, get the property independently valued by a registered valuer who factors in the lease income. This certified valuation becomes your instrument for either refinancing (to release capital for the next acquisition) or for marketing the unit to investors who want a ready income-generating property.
Step 6 — Market the Pre-Leased Unit Strategically
Target NRI investors, family offices, and HNI buyers through platforms and networks that specifically cater to investment-grade residential assets. The listing must lead with yield metrics — gross yield, net yield after maintenance, and lease expiry date — rather than bedroom count and view, which is the language of end-users, not investors.
Frequently Asked Questions
What rental yield can I realistically expect from a pre-leased luxury apartment in Gurgaon?
In prime micro-markets like Golf Course Road and DLF Phase 5, gross rental yields for luxury apartments typically range between 3.5% and 5% annually. Net yields, after maintenance charges and property management fees, usually settle between 2.8% and 4%. Fully furnished units leased to corporate tenants tend to sit at the higher end of this band.
How long does it typically take to secure a corporate tenant in Gurgaon?
A well-prepared, correctly priced unit in a sought-after project can be leased within four to eight weeks of active marketing. If the unit requires furnishing or documentation is incomplete, add another four to six weeks to that timeline. Working with a specialist relocation agency can compress this significantly.
Is a Leave and Licence Agreement better than a registered lease for a pre-leased asset?
For tenures up to 11 months, a Leave and Licence Agreement is commonly used and carries lower stamp duty. For longer corporate leases of two to five years — which are more valuable for a pre-leased asset strategy — a registered lease deed provides stronger enforceability and is viewed more favourably by lenders and prospective buyers of the investment.
Can I get a loan against a pre-leased residential property in Gurgaon?
Yes. Several banks and NBFCs offer loan-against-property products for pre-leased residential assets, often at slightly better loan-to-value ratios than vacant properties because the rental income partially services the debt. The signed lease agreement and tenant creditworthiness are key underwriting factors.
Does the quality of the tenant affect the resale value of a pre-leased apartment?
Absolutely. A lease signed with a listed company, an MNC, or a recognised institution adds credibility and reduces perceived risk for the next buyer. Investors will accept a lower yield for a tenant with a strong balance sheet. When possible, prioritise company lease agreements over individual executive leases, even if the rent offered is marginally similar.
What are the most common mistakes landlords make when trying to pre-lease a luxury apartment?
The three most frequent mistakes are overpricing based on aspirational rather than market rents, presenting an unfurnished or poorly maintained unit to corporate shortlists, and using inadequately drafted lease agreements that create disputes around maintenance or exit clauses. All three are avoidable with proper preparation and the right professional support.
Builder Floor in Gurgaon: Pre-Leased Investment Advantages

Gurgaon’s real estate market rarely sits still. Between the rapid commercial expansion along Golf Course Road, the maturing micro-markets of Sohna Road, and the steady influx of multinational tenants, the city keeps generating investment opportunities that don’t always make headlines. One such opportunity — pre-leased builder floors — deserves far more attention than it typically gets.
A pre-leased property is simply one that already has a paying tenant in place at the time of purchase. When that property is a builder floor — an independent floor unit within a low-rise residential or semi-commercial building — the combination creates a surprisingly resilient investment profile that most buyers walk past without a second glance.
Why Pre-Leased Builder Floors Stand Apart from Vacant Properties
Buying a vacant property and then hunting for a tenant is the path most investors default to. It feels straightforward, but it carries a hidden cost: the void period. Every month a property sits empty is a month of lost yield, and in Gurgaon’s premium micro-markets, that gap can stretch from two to six months depending on the season and the unit’s condition.
A pre-leased builder floor eliminates that uncertainty from day one. The rental income begins flowing the moment the sale deed is registered. For investors who are partially financing the purchase through a loan, this is particularly meaningful — the monthly rent can offset EMI payments immediately, reducing the actual out-of-pocket burden.
There is also a valuation advantage that often goes unnoticed. When a bank or financial institution assesses a pre-leased property for loan eligibility, the existing lease agreement serves as documented income proof. This frequently results in more favorable loan terms compared to a vacant unit of identical size and location. According to guidance published by the Reserve Bank of India on real estate lending, rental income from a registered lease can be factored into borrower repayment capacity, which directly influences the loan-to-value ratio a lender is willing to offer.
Beyond financing, a sitting tenant signals something else: the property has already passed a market test. A corporate tenant — the most common occupant of builder floors in Gurgaon’s established sectors — has typically conducted its own due diligence on the building’s quality, the neighborhood’s infrastructure, and the floor’s utility before signing a lease. That vetting process, done at someone else’s expense, now benefits the incoming investor.
Understanding Tenant Quality in Gurgaon’s Builder Floor Market
Not all tenants are equal. The most desirable pre-leased builder floors in Gurgaon tend to be occupied by IT firms, consulting offices, or boutique financial services companies that have chosen low-rise floors over commercial towers for reasons of cost, privacy, or flexibility. These tenants usually sign three-to-five year leases with annual escalation clauses — typically 5% to 15% — baked in. That escalation clause is essentially a contractually guaranteed income growth mechanism, something a fixed deposit or even most REITs cannot match.
Sectors like 49, 50, 57, and parts of DLF Phase 4 and 5 have seen consistent demand from such tenants. The builder floor format suits companies that want a dedicated entrance, a small parking provision, and the ability to customize their floor layout — luxuries that a commercial tower’s rigid floor plate rarely offers.
The Appreciation Story That Runs Alongside the Rental Yield
Income is only one half of the investment equation. Capital appreciation in Gurgaon’s established sectors has been quietly robust, particularly for builder floors in freehold zones where the underlying land value itself appreciates. Unlike apartments in large high-rise societies where per-unit appreciation is diluted across hundreds of owners, a builder floor investor benefits from land appreciation more directly.
Gurgaon’s infrastructure pipeline continues to strengthen this thesis. The Gurugram Metropolitan Development Authority has been actively expanding road networks and utility infrastructure across newer and older sectors alike, which historically translates into rising property values in adjacent micro-markets within a two-to-four year window after project completion.
Combining a pre-leased yield of 4% to 6% annually with capital appreciation of 8% to 12% over a five-year horizon — figures that experienced local brokers have cited as realistic in well-chosen sectors — produces a total return profile that competes seriously with most asset classes available to retail investors in India.
Evaluating a Pre-Leased Deal: What to Check Before Signing
Due diligence on a pre-leased builder floor has a few specific layers beyond the standard property check. First, verify that the lease agreement is registered, not just notarized — an unregistered lease is difficult to enforce and provides no real security. Second, review the lock-in period: the portion of the lease during which the tenant cannot exit without penalty. A 24-month lock-in on a 36-month lease is materially different from a 36-month lock-in on the same term. Third, confirm whether the tenant has exercised any renewal options, which can signal their satisfaction with the space and the likelihood of continued tenancy post your acquisition.
It is also worth examining the floor’s approved use. Many builder floors in Gurgaon sit in zones designated for mixed use or plotted development, where commercial tenancy is permitted. Others are strictly residential, and a commercial lease in such a property can create legal complications for both landlord and tenant down the line.
Frequently Asked Questions
What is a pre-leased builder floor in Gurgaon?
A pre-leased builder floor is an independent floor unit within a low-rise building in Gurgaon that already has an active tenant and a running lease agreement at the time it is offered for sale. The buyer acquires both the property and the income-generating lease simultaneously.
What rental yield can I realistically expect from a pre-leased builder floor in Gurgaon?
Rental yields typically range from 4% to 6% per annum depending on the sector, tenant profile, and remaining lease tenure. Floors with longer lock-in periods and annual escalation clauses tend to command yields toward the lower end because the income security is priced in.
Is it safe to buy a builder floor with a commercial tenant if the property is in a residential zone?
Not always. You should verify the approved land use with the relevant municipal or development authority before purchasing. Commercial tenancy in a strictly residential zone can attract legal notices and create liability for the new owner. Always consult a property lawyer and review the occupancy certificate.
How does a pre-leased property affect my home loan eligibility?
Lenders can count the documented rental income from a registered lease toward your repayment capacity, which may improve your eligible loan amount or help you qualify for the loan in the first place. The property also has a clear income track record, which some lenders view as a positive risk indicator.
What happens when the existing lease expires after I purchase the floor?
You assume the rights and obligations of the landlord under the existing lease. When the lease expires, you negotiate renewal terms directly with the tenant or find a new occupant. The advantage is that by then you will have received months or years of rental income and will have had time to assess the tenant relationship firsthand.
Are builder floors in Gurgaon a better investment than apartments in gated societies?
For income-focused investors, builder floors often offer higher rental yields and more direct land appreciation than apartments in large societies where common area costs and maintenance charges can erode net returns. However, apartments in branded developments may offer greater liquidity. The right choice depends on whether you prioritize yield, liquidity, or long-term appreciation.
Rental Property in Gurgaon: Yield Reality for Investors

Gurgaon has spent the last decade earning its reputation as one of India’s most dynamic real estate markets. But reputation and returns are two different things. If you’re evaluating rental property in Gurgaon, the most important question isn’t whether the city is growing — it clearly is — but what rental yield you can realistically expect once stamp duty, maintenance, vacancy periods, and brokerage are factored in.
This article cuts through the promotional noise to give you an honest, side-by-side look at what residential and commercial landlords are actually clearing today.
Residential Rental Yields: Steady but Modest
Across Gurgaon’s established residential corridors — Golf Course Road, DLF Phases 1–5, Sohna Road, and sectors along the Dwarka Expressway — gross rental yields for apartments typically range between 2.5% and 3.8% per annum. On a ₹1.5 crore 2BHK in Sector 57, for instance, monthly rent of around ₹28,000–₹35,000 translates to a gross yield of roughly 2.8%–3.2%.
Those numbers compress further once you apply realistic deductions. Property tax, society maintenance (often ₹5,000–₹12,000 per month for premium societies), periodic interior refurbishment, and an average vacancy window of 6–10 weeks per tenancy cycle can shave 0.5%–0.8% off the headline figure. Net yields in the 2%–3% band are the practical reality for most residential landlords.
What’s Driving Residential Demand Right Now
Demand is genuinely healthy, and that’s worth separating from the yield conversation. Corporate relocations, the expansion of GCCs (Global Capability Centres) along the NH-48 belt, and Gurgaon’s improving social infrastructure have kept vacancy rates low in well-located micro-markets. Furnished 3BHKs near Cyber City and Udyog Vihar command a rental premium of 20%–30% over unfurnished stock, which can meaningfully improve yield for investors willing to invest in fit-out.
The segment that consistently outperforms is compact, well-managed apartments in the ₹70 lakh–₹1.2 crore range. Smaller ticket sizes mean higher yield ratios, and this segment attracts the stable, salaried tenant demographic that minimises vacancy risk. According to data tracked by ANAROCK Property Consultants, Gurgaon recorded a 14% year-on-year increase in residential rental values in 2023, one of the strongest upticks in the NCR region.
Commercial Rental Yields: Higher Returns, Higher Complexity
Commercial rental property in Gurgaon tells a meaningfully different story. Office spaces in Grade-A buildings along Cyber City, Golf Course Extension Road, and the emerging Sohna Road office corridor deliver gross yields of 6%–9% per annum — more than double the residential average. Retail high-streets and ground-floor commercial units in mixed-use developments can push towards 8%–10% in the right location.
The catch is entry cost and lease structure. A 1,000 sq ft commercial unit in a premium development might be priced at ₹2 crore–₹3.5 crore outright, with leasing terms that require engaging a commercial broker, navigating longer vacancy windows between tenants, and absorbing fit-out contributions that landlords increasingly offer to attract anchor tenants. Lock-in clauses, however, work in the landlord’s favour — commercial leases of 3–9 years with annual escalation clauses of 5%–15% provide income visibility that residential contracts simply can’t match.
REITs as a Low-Friction Commercial Entry Point
For investors who want commercial yield exposure without the complexity of direct ownership, listed Real Estate Investment Trusts offer a structured alternative. Platforms regulated by SEBI allow retail investors to access income from Grade-A commercial portfolios — including Gurgaon office stock — with much lower minimum commitments. The SEBI REIT regulatory framework requires REITs to distribute at least 90% of distributable cash flows, making yield predictability a core feature of the structure.
Comparing the Two Asset Classes Side by Side
| Factor | Residential | Commercial |
|—|—|—|
| Gross yield (typical) | 2.5%–3.8% | 6%–9% |
| Net yield (after costs) | 2%–3% | 5%–7% |
| Average lease tenure | 11 months (renewable) | 3–9 years |
| Vacancy risk | Low–Moderate | Moderate–High |
| Liquidity | Higher | Lower |
| Capital appreciation potential | Moderate–High | Moderate |
The table above makes commercial property look obviously superior on yield, but liquidity and risk tolerance matter. Residential assets are far easier to exit in a time-sensitive situation, and tenant default in a commercial setting involves longer legal timelines.
Making the Right Call for Your Portfolio
There’s no universal right answer — only the right answer for your capital base, risk appetite, and investment horizon. A few principles, though, hold consistently across Gurgaon’s rental market.
Location quality is non-negotiable. Even within the same sector, proximity to a Metro station, a reputed school, or a major employment hub can mean a 15%–25% rental premium. Investors who buy at the city’s edge hoping for yield arbitrage frequently find that vacancy periods erase the advantage.
Don’t benchmark against peak asking rents. Landlord listings routinely price 10%–15% above what transacts. When underwriting a purchase, base your yield calculation on rents that have actually been signed in comparable units within the last 90 days — your broker should be able to provide registered agreement data.
Factor in the interest rate environment. If a property is financed, net yield after EMI servicing is the only number that matters. At current home loan rates of 8.5%–9.5%, a residential property yielding 3% gross is cash-flow negative from day one. That’s not necessarily a dealbreaker if capital appreciation is the primary thesis, but it should be entered into with clear eyes.
Gurgaon remains one of the most compelling rental markets in urban India. The discipline is in pricing your specific asset honestly — and not letting the city’s broader momentum substitute for rigorous per-unit math.
Frequently Asked Questions
What is the average rental yield for residential property in Gurgaon?
Gross yields for residential apartments in Gurgaon typically fall between 2.5% and 3.8% per annum, depending on location, unit size, and furnishing level. After accounting for maintenance, vacancy, and property tax, net yields usually settle in the 2%–3% range.
How do commercial rental yields in Gurgaon compare to residential?
Commercial properties — particularly Grade-A office spaces in Cyber City and Golf Course Extension Road — deliver gross yields of 6%–9%, roughly double the residential average. However, they come with higher entry costs, longer vacancy windows, and lower liquidity.
Which localities offer the best rental returns in Gurgaon?
For residential rentals, sectors near Cyber City, Udyog Vihar, and the Dwarka Expressway corridor perform consistently well due to proximity to large employers. For commercial returns, Cyber City, Golf Course Road, and Sohna Road office corridors lead the market.
Is rental property in Gurgaon cash-flow positive?
For financed residential purchases at current home loan rates of 8.5%–9.5%, most acquisitions are cash-flow negative, meaning rental income does not cover the EMI. Investors typically offset this with expected capital appreciation. Unleveraged or lightly leveraged purchases are more likely to generate positive cash flow.
What risks should I consider before investing in Gurgaon rental property?
Key risks include vacancy periods between tenancies, tenant default (especially in commercial leases), maintenance costs in aging societies, and broader market illiquidity during economic slowdowns. Regulatory changes affecting rental agreements and property tax assessments are also worth monitoring.
Are REITs a good alternative to direct rental property investment in Gurgaon?
REITs offer exposure to commercial rental income — including Gurgaon office assets — with significantly lower capital commitment and higher liquidity than direct property ownership. SEBI mandates that REITs distribute at least 90% of distributable income, making them a yield-focused instrument, though they lack the direct control and capital appreciation potential of owning an asset outright.
Commercial Property for Lease in Gurgaon: Legal Checklist
Gurgaon’s commercial real estate market moves fast. A promising office in Cyber City or a retail unit on MG Road can attract multiple interested tenants within days, and that urgency can push businesses into signing lease agreements without adequate legal scrutiny. The consequences — locked-in unfair rent escalation clauses, unexpected maintenance liabilities, or disputed exit terms — can cost a company far more than a few weeks of due diligence would have.
This checklist is designed for business owners, startup founders, and procurement managers who are evaluating commercial property for lease in Gurgaon and want to avoid the most common legal pitfalls.
Key Documents to Verify Before You Negotiate
Before you even begin discussing rent, your legal team or a qualified property lawyer should verify the following documents directly from the landlord.
Title and Ownership Verification
Confirm that the landlord actually holds clear, marketable title to the property. Request the original sale deed, and cross-check ownership records with the Haryana government’s HRERA registration portal and the relevant tehsil land records office. In Gurgaon, properties in mixed-use or special economic zones sometimes have layered ownership structures involving developers, landowners, and housing societies — each layer can create disputes that affect your right to occupy the space.
Occupancy and Completion Certificates
An Occupancy Certificate (OC) issued by the Municipal Corporation of Gurugram confirms that the building was constructed according to approved plans and is legally fit for use. Many commercial buildings in Gurgaon — especially in newer micro-markets like Sohna Road and Southern Peripheral Road — are leased out before an OC is issued. Operating from a building without a valid OC can expose your business to enforcement action and insurance complications.
Zoning and Land-Use Compliance
Verify that the property is zoned for your intended use. A space marked for general commercial use may not permit manufacturing, warehousing, or certain service categories. The Gurugram Metropolitan Development Authority (GMDA) maintains land-use maps that can confirm whether a property’s current use aligns with its permitted classification.
Encumbrance Check
Obtain an encumbrance certificate covering at least the past 13 years. This confirms whether the property carries any outstanding mortgages, liens, or litigation. A property under bank mortgage can be seized by the lender even while you are a paying tenant, so this step is non-negotiable.
Critical Lease Clauses to Scrutinise
Once documents check out, the lease agreement itself demands equally careful attention. Indian lease law under the Transfer of Property Act, 1882 gives landlords and tenants considerable freedom to set their own terms — which means poorly drafted agreements heavily favour whoever wrote the first draft.
Rent Escalation and Lock-In Period
Most commercial leases in Gurgaon include a rent escalation clause, typically 5–15% every one to three years. Negotiate a cap, and ensure the escalation formula is written explicitly rather than left to the landlord’s discretion. Similarly, review the lock-in period carefully. A three-year lock-in with a steep penalty for early exit can be crippling if your business pivots or downsizes.
Maintenance, CAM Charges, and Fit-Out
Common Area Maintenance (CAM) charges in Gurgaon’s Grade A commercial buildings are often significant and can rise independently of your base rent. The lease should specify exactly which costs are included in CAM, how they are calculated, and whether you have the right to audit the landlord’s CAM accounts. If you are taking an unfinished shell space, clarify in writing who bears the cost of electrical fit-out, HVAC, and partition work — and whether the landlord’s fit-out contribution (if any) is a loan or a concession.
Exit, Renewal, and Sub-Letting Rights
Negotiate a clear termination notice period — 90 to 180 days is standard for large commercial spaces. Confirm whether you have a right of first refusal to renew at the end of the lease term, and whether you can sub-let or assign the lease if your circumstances change. Some agreements prohibit sub-letting entirely; others allow it only with landlord consent, which can become a point of dispute.
Security Deposit and Refund Terms
Security deposits for commercial property for lease in Gurgaon typically range from two to six months’ rent, with the exact amount varying by building grade and landlord. The agreement must specify the exact refund timeline after lease expiry, the conditions under which the landlord can make deductions, and — critically — whether the deposit earns interest. Without a written refund clause, disputes over deposit return are among the most common reasons tenants end up in arbitration.
Dispute Resolution Clause
Ensure the lease specifies arbitration as the primary dispute resolution mechanism and names a governing jurisdiction. Given Gurgaon’s commercial density, many landlords prefer Delhi or Gurugram courts; confirm this in advance so you are not forced into an inconvenient forum.
Frequently Asked Questions
Is it mandatory to register a commercial lease agreement in Gurgaon?
Yes. Under the Registration Act, 1908, any lease agreement for a period exceeding 11 months must be registered with the Sub-Registrar’s office. Unregistered leases lasting more than 11 months are not admissible as evidence in court, which significantly weakens a tenant’s legal position in any dispute.
What is a typical lock-in period for commercial leases in Gurgaon?
Lock-in periods commonly range from one to three years for small and mid-size spaces, and up to five years for large floor plates in Grade A buildings. The key issue is the early exit penalty — negotiate this to be limited to the remaining rent for the lock-in period rather than the full lease tenure.
Can a landlord increase rent during the lock-in period?
Not if the lease agreement explicitly prohibits it. Ensure the agreement states that no rent revision will apply during the lock-in period, even if the escalation clause provides for annual increases.
Who is responsible for property tax on a leased commercial property?
Unless the lease agreement explicitly shifts the obligation, property tax is the landlord’s liability as the owner of record. However, some landlords attempt to pass this cost to tenants through CAM charges — review the CAM definition carefully to ensure property tax is excluded.
How much security deposit is standard for commercial spaces in Gurgaon?
For most commercial properties in Gurgaon, security deposits range from two to six months of rent. Grade A buildings in Cyber City or DLF phases tend to ask for three to six months, while secondary markets may accept two to three months. Always insist on a written refund clause with a specific timeline.
What happens if the building lacks a valid Occupancy Certificate?
Operating from a building without an OC can lead to municipal enforcement action, including sealing of premises. It may also void your commercial insurance policy and complicate regulatory filings. If an OC is pending, negotiate an indemnity clause and a timeline by which the landlord must obtain it — or consider walking away.
Office Space for Rent in Gurgaon: Attract Premium Tenants
Gurgaon — now officially Gurugram — has firmly established itself as India’s premier corporate address. The city’s Golf Course Road, Cyber City, and NH-48 corridors are home to the regional and global headquarters of companies that span finance, technology, consulting, and pharmaceuticals. For a landlord, that concentration of multinational demand is an opportunity. But it also sets the bar high: Fortune 500 occupiers apply the same due-diligence rigour to a lease decision in Gurgaon as they do in London or Singapore.
If you own or manage commercial property and want to compete seriously for that tier of tenant, the quality of your building is only the starting point. Understanding what large corporates actually evaluate — and how the best-performing assets in the city differentiate themselves — is what turns a vacancy into a long-term, high-value lease.
What Fortune 500 Tenants Actually Look For
Large occupiers are not simply shopping for square footage. Their real estate teams conduct structured scorecards that assess a building across several dimensions before a shortlist is even created.
Grade-A specifications are non-negotiable. Raised flooring, a minimum floor-to-ceiling height of 2.75 metres, a floor plate of at least 20,000 sq ft, and a power backup of 1 VA per sq ft are baseline requirements for most multinationals. HVAC systems must be individually controlled by zone, and the building’s common areas must be maintained to a standard that reflects the tenant’s own brand expectations.
Green certification changes the conversation. According to the Indian Green Building Council, India now has over 10 billion sq ft of registered green building footprint, and large corporates — many of whom have signed the Science Based Targets initiative — are contractually obligated to occupy certified space wherever possible. A LEED Platinum or IGBC Gold rating is no longer a differentiator; in many RFPs it is a threshold criterion. If your building lacks certification, you will simply not appear on the shortlist.
Connectivity and last-mile access matter enormously. Proximity to the Rapid Metro or the Delhi Metro network is factored into employee commute modelling. Buildings within 500 metres of a metro station consistently command a 10–15% rental premium over comparable stock that requires a cab or shuttle. If your asset is not walkable from transit, invest in a dedicated shuttle partnership before your next vacancy.
Vendor and fitout flexibility is underrated. Many Fortune 500 tenants arrive with a preferred interior design firm, a global MEP contractor, and a specific furniture programme. Landlords who impose restrictive vendor panels or charge punitive fitout management fees lose deals quietly — tenants rarely tell you the real reason they walked away.
Finally, occupiers at this level send their global real estate and legal teams to review leases. Documents that contain unusual or non-standard clauses — particularly around exit penalties, maintenance cost caps, and reinstatement obligations — slow down deal timelines dramatically. Work with a property lawyer who has experience structuring Grade-A commercial leases before you enter any serious negotiation.
How to Position Your Asset and Justify Premium Rents
Attracting the right tenant is one challenge; achieving the rent you want is another. The good news is that the two goals are aligned. The same investments that make your building eligible for Fortune 500 consideration also provide the evidence base for a premium rent discussion.
Benchmark honestly, then invest with intention. The market for office space for rent in Gurgaon spans a wide range — from sub-₹60 per sq ft per month in peripheral locations to ₹200 and above on prime Golf Course Road addresses. Before you set an asking rent, commission an independent valuation and a competing-property audit. Identify the two or three assets in your micro-market that are consistently winning high-quality tenants, and close the gap on whatever they offer that you do not.
Amenity programming is now a hard asset feature. The pandemic permanently shifted what tenants value in an office building. A cafeteria with multiple food operators, a wellness centre, an EV charging infrastructure in the basement, and a bookable podcast or video-conferencing studio are no longer luxury add-ons. They are the reasons a global occupier’s employees choose to commute rather than work from home — and they are reasons a real estate director can present to the CFO when justifying a ₹180 rent versus a ₹140 alternative.
Offer structured flexibility without sacrificing revenue. Large tenants often want an anchor lease on core floors and the option to expand into adjacent space as headcount grows. Building a formal right-of-first-refusal mechanism into your lease structure — alongside a managed flex floor operated through a third-party partner — allows you to accommodate that demand without holding dead inventory. According to JLL India’s commercial research, flex space within Grade-A buildings has grown from a niche product to a mainstream leasing strategy across Gurgaon’s prime corridors.
Invest in property management as a front-of-house function. The first impression a Fortune 500 real estate director forms of your building is rarely the brochure — it is the lobby experience during a site visit. A responsive, tech-enabled facility management team, a digital visitor management system, and a building app that lets tenants raise service requests are signals that you operate at the standard they expect. Poor property management is the single most common reason multinational tenants do not renew, even when the location is right.
Signing a long-term lease with a creditworthy global occupier is the most reliable way to maximise the capital value of a commercial asset. The investment required to reach that standard is real, but so is the return — in rent, in lease length, and in the asset’s attractiveness to institutional investors if you choose to exit.
Frequently Asked Questions
What is the average rent for Grade-A office space for rent in Gurgaon?
Rents vary significantly by micro-market. Cyber City and Golf Course Road command ₹150–₹220 per sq ft per month for Grade-A stock, while NH-48 and Sohna Road corridors typically range from ₹80–₹130. Amenity levels, green certification, and floor plate size all influence where a specific asset sits within that band.
How long does it typically take to close a lease with a Fortune 500 tenant?
Expect a minimum of four to six months from initial enquiry to executed lease. Global corporates involve multiple internal stakeholders — real estate, legal, finance, HR, and often a regional leadership sign-off. Landlords who have their technical documents, title certificates, and lease drafts pre-prepared can compress this timeline meaningfully.
Is LEED certification worth the investment for a Gurgaon commercial building?
For landlords targeting multinational tenants, yes — almost without exception. The certification cost is typically recovered within one to two lease cycles through a combination of higher achieved rents, lower vacancy periods, and the ability to retain tenants at renewal who face ESG reporting obligations.
What lease structures do Fortune 500 tenants prefer in India?
Most large occupiers prefer a bare-shell or warm-shell lease with a tenant fitout, a lock-in period of three to five years, and an exit option thereafter. They typically negotiate a rent-free period to offset fitout costs, annual escalation clauses of 5–15%, and a formal expansion option on adjacent floors.
How important is parking supply when leasing to large corporate tenants?
Parking is a significant factor, particularly for tenants whose leadership teams are car-dependent. A ratio of at least one car park space per 1,000 sq ft of leased area is the general expectation, and EV charging bays are increasingly a stated requirement rather than a preference.
Can smaller landlords compete with institutional-grade buildings for quality tenants?
Yes, but only by being genuinely excellent in a specific area — whether that is a unique location, a distinctive design, or an unusually responsive management team. Smaller buildings that try to compete on every dimension with large institutional assets rarely win. Those that identify a specific tenant segment and build everything around that segment’s needs often build strong, loyal occupier relationships.