Residential Property Investment Long-Term vs Short-Term Guide

Gurgaon’s residential market has delivered some of the sharpest price appreciation in India over the past decade — yet owners consistently struggle with the same question: should I sell now, rent it out, or simply wait? The answer isn’t universal. It depends on your asset’s micro-location, your liquidity needs, and current market momentum. This framework gives you a structured way to think through residential property investment long-term vs short-term so that your decision is driven by data, not anxiety.
Reading the Gurgaon Market Before You Decide
Before picking a strategy, you need a clear-eyed view of where prices and rentals actually stand. According to Knight Frank’s India Real Estate reports, Gurgaon’s premium micro-markets — Golf Course Road, DLF 5, and sectors along the Dwarka Expressway — have seen 18–28% capital appreciation over a 24-month window ending in late 2024. That is meaningful, but it is not uniform across the city.
Ask yourself three diagnostic questions before you commit to any exit path:
– What is the current rental yield in your sector? Gurgaon’s average gross rental yield sits between 2.8% and 3.8%. If your sector clears 3.5%, renting becomes competitive with fixed deposits once tax and vacancy costs are factored in.
– How long have you held the asset? Properties held beyond two years qualify for long-term capital gains tax treatment, meaningfully changing your net realisation on a sale.
– Is the locality supply-constrained or oversupplied? Sectors with significant new launches in the pipeline — particularly in New Gurgaon — face short-term rental and resale pressure that can erode both strategies.
These three data points alone will eliminate at least one of your three options before you run a single spreadsheet model.
The Case for Each Strategy — and When It Breaks Down
Flipping (Short-Term Sale)
Flipping makes the most sense when you bought during a pre-launch or under-construction phase and the project is now ready or close to possession. The builder discount you captured — often 15–22% below circle rate — becomes your margin. However, flipping inside two years triggers short-term capital gains tax at your income tax slab rate, which can swallow 30% of that margin for higher-bracket taxpayers. If you’re evaluating residential property investment long-term vs short-term purely on post-tax returns, a flip that clears possession within 30 months of purchase often underperforms a disciplined hold by a surprising degree.
Flipping also works well when the broader market is peaking — which requires genuine read of absorption rates, not just headline price indices. Speak to three registered brokers active in your specific sector before concluding the market is at its top.
Renting (Yield Play)
Renting suits owners who don’t need liquidity immediately and hold a property in a high-demand corridor — near corporate hubs in Cyber City, Udyog Vihar, or the emerging sectors along NH-48. A 3-bedroom apartment in Sector 54 currently commands ₹65,000–₹85,000 per month, while a similar unit in Sector 89 may yield ₹28,000–₹38,000. The gap matters because your holding cost — maintenance, society charges, property tax — is roughly the same.
The risk in a rental strategy is vacancy drag and tenant-related legal complexity. India’s rental market still operates under older tenancy laws in Haryana, though the Model Tenancy Act is gradually being adopted. Structure a leave-and-licence agreement carefully, and budget 8–10% of gross rent annually for maintenance, brokerage, and vacancy periods.
Holding (Long-Term Capital Appreciation)
A pure hold strategy — no tenant, no sale — is defensible only if you have zero carrying-cost pressure, your sector has strong infrastructure triggers on the horizon (metro extension, expressway completion, SEZ activation), and you can afford to wait 5–7 years for the next liquidity cycle. Holding an untenanted property in Gurgaon’s high-rise market is expensive: society maintenance alone can run ₹8,000–₹20,000 per month depending on the project. Unless appreciation is expected to exceed 10–12% annually, an empty hold rarely beats a tenanted hold.
The most defensible position for most investors is a tenanted hold — rent the property, cover carrying costs, wait for the market cycle to peak, then sell with a long-term capital gains advantage. This hybrid approach is often overlooked in simplistic hold-vs-sell debates.
Building Your Personal Decision Matrix
Rather than guessing, map your situation against four variables and score each strategy from 1–5:
1. Liquidity need (high need favours flipping; low need favours hold or rent)
2. Rental yield of your sector (above 3.2% favours renting)
3. Holding period so far (under 2 years nudges toward waiting before selling)
4. Infrastructure catalyst proximity (metro within 1 km or highway upgrade within 18 months adds 1 point to hold)
This is not a proprietary algorithm — it is a structured way to make a decision you have probably been delaying. The Gurgaon market rewards owners who are deliberate. The owners who lose are typically those who flip too early and miss the appreciation, or those who hold too long without a tenant and bleed on carrying costs.
Whatever path you choose, revisit the decision annually. Market conditions in Gurgaon shift fast, and a strategy that made sense in early 2023 may need recalibration by mid-2025.
Frequently Asked Questions
Is renting out my Gurgaon flat worth it given low yields?
Gross yields of 3–3.5% look modest, but when you factor in that a tenanted property covers most carrying costs and continues appreciating, the total return often outperforms a premature sale. The key is choosing sectors with strong corporate tenant demand rather than purely residential catchments.
What is the tax difference between a short-term and long-term property sale?
Properties sold within 24 months of purchase attract short-term capital gains tax at your applicable income slab rate. Properties held beyond 24 months qualify for long-term capital gains tax, currently at 12.5% without indexation benefit following the 2024 Budget revision. This distinction is central to any residential property investment long-term vs short-term calculation.
How do I estimate the right asking rent for my Gurgaon property?
Compare active listings on PropTiger and NoBroker for your specific sector and configuration. Discount listed rents by 8–12% to get realistic transacted rates. Factor in furnishing level — a semi-furnished 3BHK commands roughly 15–20% more than an unfurnished equivalent.
When does flipping actually make financial sense in Gurgaon?
Flipping makes sense when you entered at a pre-launch discount of over 15%, the project is approaching possession, and you are in a lower income tax bracket that makes short-term gains less punishing. It rarely makes sense mid-cycle for someone who bought at market price.
Should I use a property manager if I decide to rent?
For non-resident owners or those with limited time, a professional property manager charging 8–10% of monthly rent is worth considering. They handle tenant screening, rent collection, and maintenance escalations — reducing the vacancy and legal risk that makes DIY landlording stressful.
Aspirational Property Luxury Home Buying: When to Upgrade
Somewhere between paying off your second mortgage and watching your investment portfolio quietly compound, a thought surfaces: is it time to upgrade? For many successful professionals and investors, the leap from mid-segment housing into aspirational property luxury home buying isn’t just a lifestyle choice — it’s a calculated financial move that deserves the same rigour as any other major investment decision.
But knowing when to act, how to prepare your finances, and what levers to pull at the negotiating table separates buyers who thrive in the luxury segment from those who overextend themselves.
The Financial Triggers That Signal You’re Ready
Luxury property purchases rarely happen impulsively — at least not the ones that work out well. The buyers who make the transition smoothly share a handful of consistent financial markers.
Equity has matured into meaningful leverage. If your current property has appreciated significantly and you’re sitting on substantial equity, that capital can serve as a down payment without liquidating other investments. In most luxury markets, lenders expect 20–30% down, so your equity position matters enormously.
Your income streams have diversified. Relying on a single salary to service a high-value mortgage is a vulnerability. Buyers who upgrade successfully often have two or more income sources — a primary salary, rental income, dividends, or business distributions — providing buffer against rate shifts or income disruption.
Your debt-to-income ratio is comfortable below 35%. Luxury lenders scrutinise this number closely. According to the Consumer Financial Protection Bureau, a DTI above 43% typically disqualifies buyers from qualified mortgage products, making a lower ratio not just preferable but practically essential.
Your emergency fund remains untouched. One mistake mid-segment buyers make when upgrading is draining reserves to close the deal. Luxury properties carry higher ongoing costs — maintenance, insurance, property taxes, and HOA fees — that can run 2–4% of the purchase price annually. Your safety net should survive the purchase intact.
If three or four of these markers apply to you simultaneously, the financial foundation is there. The question becomes one of timing.
Reading the Market: Timing Signals That Actually Matter
Luxury real estate doesn’t move in lockstep with the broader housing market. High-end inventory often behaves counter-cyclically: when mass-market properties are scarce, luxury stock can sit longer, giving informed buyers real negotiating room.
Days on market is your clearest signal. In a balanced luxury market, premium properties sell in 60–120 days. When average days on market in your target neighbourhood stretch past 150, sellers are feeling pressure — and motivated sellers negotiate differently than confident ones.
Watch for price reduction patterns. A single price cut is routine. Two reductions on the same property within 90 days signals the seller’s expectations have fundamentally shifted. That’s the moment to make a serious approach.
Interest rate windows matter more at higher loan values. A 0.5% difference on a $1.5 million mortgage represents roughly $4,500 per year in interest. Monitoring rate cycles isn’t just smart — at this price point, it’s essential. Resources like Freddie Mac’s Primary Mortgage Market Survey track weekly rate movement and give you an objective baseline for timing your application.
Lifestyle readiness is a timing signal too. Are your children at a stable point in school? Is your business or career in a phase where relocating serves rather than disrupts growth? Luxury property purchases often come with longer settlement periods and more complex logistics. Aligning those practicalities with your personal calendar prevents costly forced decisions.
Negotiation Tactics That Work in the Luxury Segment
High-value real estate negotiation operates on different social and financial dynamics than mid-segment transactions. Sellers of luxury properties often have deep emotional attachment to the asset, meaning pure price aggression can backfire. Strategic, respectful positioning tends to produce better outcomes.
Lead with a credibility package, not just an offer. Before submitting a price, your agent should deliver a pre-approval letter, proof of funds for the deposit, and a brief buyer profile that humanises you as a steward of the property. Luxury sellers frequently turn down higher offers from buyers who feel uncertain or transactional.
Negotiate terms, not just price. Closing timelines, included furnishings, early access for contractors, and settlement flexibility are all negotiable and sometimes worth more than a price reduction. A seller who needs 90 days to vacate will take a slightly lower number from a buyer who accommodates that need.
Use inspection findings as a second negotiation. Even in prime condition, a luxury home at this price tier will surface inspection items. Rather than asking for repairs, request a price adjustment equivalent to the remediation cost. This keeps the deal clean and gives you control over the quality of work.
Understand the seller’s motivation before you write anything. Is this a divorce, a relocation, an estate sale, or a discretionary upgrade? Each scenario carries different pressure points. A relocating seller values certainty and speed. An estate sale trustee values simplicity and a clean contract. Knowing the motivation lets you tailor your offer to solve their actual problem — and aspirational property luxury home buying becomes far less adversarial when both sides feel understood.
The upgrade from mid-segment to luxury isn’t a single transaction — it’s the beginning of a different relationship with real estate as a wealth-building vehicle.
Frequently Asked Questions
How much equity should I have before upgrading to a luxury property?
Most financial advisors suggest having at least 20–30% of the luxury property’s purchase price available from equity or liquid assets. This covers the typical down payment requirement and leaves room for closing costs, which in luxury transactions can reach 3–5% of the purchase price.
Is it better to sell my current home before buying a luxury property?
In most cases, yes. Carrying two mortgages simultaneously — particularly at high loan values — creates significant financial exposure. Selling first gives you a clear equity figure, a cleaner balance sheet for lender assessment, and stronger negotiating confidence when you make your luxury offer.
What are the ongoing costs I should budget for in a luxury home?
Beyond your mortgage, budget approximately 2–4% of the property’s value annually for maintenance, insurance, and property taxes. Premium finishes, larger land areas, pools, and smart-home systems all carry higher upkeep costs than standard mid-segment homes.
Do luxury property sellers negotiate more or less than mid-segment sellers?
They negotiate differently. Luxury sellers often have less financial urgency, so pure price pressure rarely works well. However, they tend to respond strongly to terms-based negotiation — flexible timelines, clean contracts, and buyers who present credibly. The emotional dimension of selling a prized home is also real and shouldn’t be underestimated.
How long does it typically take to close on a luxury property?
Luxury transactions often run 45–90 days from accepted offer to settlement, though some complex deals — particularly those involving trust structures, international buyers, or significant contingencies — can extend beyond 90 days. Build this timeline into your planning.
Should I use a specialist luxury real estate agent?
Yes. Agents who work exclusively or primarily in the luxury segment have access to off-market listings, relationships with listing agents, and negotiation experience specific to high-value transactions. Their commission is typically offset many times over by the terms they secure and the mistakes they help you avoid.
Property Buying Guidance RERA: Registered vs Non-RERA Projects
Buying a home is probably the largest financial decision most people ever make. Yet for years, Indian real estate worked almost entirely on trust — trust that a builder would deliver on time, that the flat you booked matched the one you’d eventually receive, and that your money wasn’t quietly being diverted to another project. The Real Estate (Regulation and Development) Act, 2016, changed that equation significantly. But “significantly” is not the same as “completely,” and understanding the gap is the heart of smart property buying guidance RERA has made possible.
What RERA Registration Actually Guarantees
When a project is registered with the Real Estate Regulatory Authority, the developer is bound by a specific set of legal obligations — not just promises in a brochure.
Escrow protection for your money. Developers must deposit 70% of buyer funds into a dedicated escrow account, withdrawable only for construction costs of that specific project. This single rule dismantled the most common fraud in Indian real estate: collecting money from Project A buyers to fund Project B.
Carpet area transparency. Builders must quote and sell on carpet area, not the fuzzy “super built-up area” figure that historically inflated prices by 25–40%. The RERA Act’s official definition on India Code makes this measurement legally binding.
Delivery timelines with teeth. The registered completion date is legally enforceable. If the builder misses it, you’re entitled to either a full refund with interest or monthly compensation for every month of delay — whichever you prefer.
Structural defect liability. If structural defects appear within five years of possession, the developer must fix them at no cost to you. No more arguing over who is responsible.
Advertising accountability. Any advertisement — online listing, brochure, site visit promise — is legally binding once a project is RERA-registered. Developers can’t show you a model flat loaded with premium fittings and then deliver bare walls.
Access to a dedicated tribunal. Disputes go to the RERA authority or its appellate tribunal, not the sluggish civil courts. Complaints are supposed to be resolved within 60 days.
For genuine property buying guidance RERA compliance gives you real ammunition. You can verify a project’s registration number on your state’s official RERA portal (most states have one; Maharashtra’s MahaRERA and UP-RERA are among the most active), check the developer’s track record of past projects, and download the registered site plan before signing anything.
What RERA Does Not Protect You From
RERA is a powerful framework, but treating it as a complete safety net is a mistake. Here’s where the protection ends.
Plots and completed buildings are largely excluded. RERA applies to under-construction projects above a certain size threshold. If you’re buying a resale flat or a developed plot below the threshold, you’re outside RERA’s direct jurisdiction.
Registration doesn’t mean the project is viable. A developer can register a project and still go broke mid-construction. RERA doesn’t vet a builder’s financial health or audit whether the escrow is actually being maintained correctly — enforcement varies sharply by state.
Title risk remains your problem. RERA does not verify land title. If the developer doesn’t have clean ownership of the land — encumbrances, disputed ownership, land-use violations — you can win a RERA case and still lose your flat. A proper title search by an independent lawyer is non-negotiable regardless of RERA status.
Agricultural or conversion land issues. In many states, agricultural land must be legally converted for residential use before construction. RERA registration doesn’t confirm this conversion happened. Buying on unconverted land can leave you without an occupancy certificate even after the building is complete.
Force majeure delays are exempt. The Act allows developers to claim force majeure — acts of God, government-ordered shutdowns — as a reason to extend timelines without penalty. The COVID-19 period showed how broadly this can be applied.
Non-RERA projects carry all of the above risks, amplified. Without registration, there’s no escrow obligation, no standard carpet area calculation, no legally binding timeline, and no RERA tribunal to approach. You’re left pursuing remedies through consumer courts or civil courts — slower, costlier, and less certain. The National Consumer Disputes Redressal Commission is an option, but cases routinely take years.
The practical lesson: RERA registration is a necessary condition for buying with reasonable confidence, but it is not a sufficient condition for skipping due diligence.
Frequently Asked Questions
How do I check if a project is genuinely RERA-registered?
Visit your state’s official RERA portal and search by the project name or registration number. Every registered project must display its RERA number in all advertisements. If a developer quotes a registration number but it doesn’t appear on the portal, walk away.
Can I get a refund if a RERA-registered project is delayed?
Yes. Under the Act, if a developer misses the registered completion date, you can claim a full refund with interest at a prescribed rate (currently linked to the State Bank of India’s lending rate plus 2%). Alternatively, you can choose to stay in the project and receive monthly delay compensation instead.
Does RERA cover commercial property purchases too?
Yes. RERA applies to both residential and commercial real estate projects above the prescribed size threshold (generally more than 500 square metres of land or more than eight units). Buyers of commercial office space or retail units have the same rights as residential buyers under the Act.
What if a developer registers the project but then goes bankrupt?
This is the Act’s most significant blind spot. RERA doesn’t guarantee project completion if the developer is insolvent. In such cases, buyers typically have to approach the National Company Law Tribunal under insolvency proceedings, where they are treated as financial creditors — a process that can take years with uncertain outcomes.
Is a RERA-registered project guaranteed to have a clear land title?
No. RERA registration requires the developer to submit title documents, but the authority does not conduct an independent legal audit of the title. You must hire your own property lawyer to conduct a title search and verify that the land is free of encumbrances, mortgages, and litigation before you pay any booking amount.
Are plots in a gated community covered by RERA?
Plotted developments where the promoter carries out any kind of development work (laying roads, drainage, common amenities) are generally covered by RERA. Pure resale of developed plots between private individuals typically is not. Check your state’s specific RERA regulations, as some states have extended coverage further than the central Act requires.
Dream Home Search Strategy: Stop Scrolling, Start Moving In
You’ve been doing it for months—opening the same real estate apps during lunch, saving listings you’ll never revisit, and lying awake wondering whether that three-bedroom in the good school district is still available. This kind of browsing feels productive, but without a real dream home search strategy behind it, it’s the housing-market equivalent of window shopping with no wallet.
The good news: a structured approach doesn’t require a real estate license or a spreadsheet obsession. It just requires you to make a few key decisions before you open another tab.
Build Your Foundation Before You Browse
The single biggest mistake buyers make is starting with listings instead of starting with themselves. Before your dream home search strategy can work, you need to establish three non-negotiables.
1. Fix your number first. Not a vague range—an actual pre-approval. According to the Consumer Financial Protection Bureau, getting pre-approved early gives you a realistic ceiling and signals seriousness to sellers in competitive markets. Without it, every listing you fall in love with is a fantasy.
2. Separate must-haves from nice-to-haves in writing. Sit down with everyone involved in the purchase and create two columns. Must-haves are deal-breakers: minimum bedrooms, school district, maximum commute time. Nice-to-haves are bonuses: a soaking tub, a three-car garage, a chef’s kitchen. Buyers who skip this step routinely tour homes that can never satisfy everyone—and then argue about it on the drive home.
3. Define your timeline with a backward calendar. When do you need to be in the home? Work backward from that date, accounting for closing (typically 30–45 days), offer negotiation, home inspection, and serious searching. This calendar keeps urgency real without letting it become panic.
Once these three things are documented, your dream home search strategy has a spine. Now browsing becomes evaluating.
Run a Search Like a Professional, Not a Hobbyist
Professional buyers—investors, real estate agents buying for themselves—treat the search phase like a funnel, not a feed. Here’s how to adopt the same mindset.
Set alerts with precision, then leave the apps alone
Most listing platforms let you save a search and receive email or push notifications the moment a matching home hits the market. Set this up with your actual criteria—square footage, bedroom count, zip codes, maximum price—then stop refreshing manually. New listings in desirable areas can go under contract within days, so a well-configured alert actually beats compulsive scrolling for speed.
Tour in batches, not one-offs
Random, isolated tours make it nearly impossible to compare homes accurately. Instead, block a half-day on consecutive weekends and schedule three to five tours back-to-back. Take photos of every room (with the agent’s permission), and spend five minutes in the car immediately after each tour rating the home against your must-have list. Memory degrades fast—your notes won’t.
Track everything in one document
Create a simple comparison tracker: rows for each home, columns for price, square footage, must-have checklist score, gut feeling (yes, this matters), and any deal-breaker observations. When you reach the offer stage, this document will save you from second-guessing—or from accidentally making an offer on a home that quietly missed three of your requirements.
Work with an agent who communicates in your style
A buyer’s agent doesn’t cost you anything directly—the seller typically covers commission—so there’s no reason to go unrepresented. The right agent sends you homes before they hit the public portals, flags issues you’d miss, and negotiates with context you don’t have. Interview two or three and choose the one who listens more than they talk.
From Offer to Keys: Don’t Let the Process Derail You
A surprising number of buyers execute a strong dream home search strategy and then lose momentum once they’re under contract. This final phase has its own structure.
Make clean offers. In competitive markets, clarity matters. An offer with a well-organized pre-approval letter, reasonable contingencies, and a flexible closing date stands out. Your agent can advise on local norms—what’s competitive in Phoenix is very different from rural Vermont.
Use the inspection as information, not ammunition. A home inspection isn’t a punch list for demanding perfection; it’s a tool for understanding what you’re buying. Focus repair requests on safety issues and significant defects, not cosmetic imperfections. Buyers who treat every inspection finding as a crisis frequently kill deals they should have closed.
Stay in close contact with your lender. The period between accepted offer and closing involves a lot of documentation. Respond to your lender’s requests within 24 hours whenever possible. Delays here are one of the most common reasons closings get pushed—or collapse entirely.
Follow this sequence and your dream home search strategy becomes a pipeline, not a lottery.
Frequently Asked Questions
How long does a typical dream home search take?
Most buyers spend two to six months actively searching, though this varies significantly by market. In high-demand cities, having your finances ready before your search begins can meaningfully shorten the timeline.
Should I search online myself or just rely on my agent?
Both. Your agent has access to the MLS and off-market opportunities you won’t see publicly, but staying engaged with major listing platforms keeps you informed and helps you calibrate your expectations in real time.
How many homes should I tour before making an offer?
There’s no magic number, but most buyers who find a home they love have toured somewhere between five and fifteen properties. Touring fewer than five often means you lack comparison context; touring more than twenty without offering can signal that criteria need re-evaluation.
What if I keep losing bidding wars?
Revisit your pre-approval limit, your must-have list, and your target neighborhoods. Sometimes the fix is a slightly larger budget; sometimes it’s expanding the search radius by five miles. A pattern of losses usually points to a mismatch between expectations and market reality.
Is it okay to make an offer on the first home I tour?
Absolutely, if it genuinely meets your documented criteria. Waiting arbitrarily when the right home appears is how buyers lose great properties. The structured groundwork you did before searching is exactly what makes early confidence possible.
When should I walk away from a deal?
Walk away if the inspection reveals safety or structural issues the seller won’t address, if the appraisal comes in significantly low and the seller won’t negotiate, or if your financial situation changes materially before closing. Emotional attachment is normal, but a disciplined dream home search strategy accounts for exits as well as entries.
Residential Property Investment Gurgaon 2025 Guide
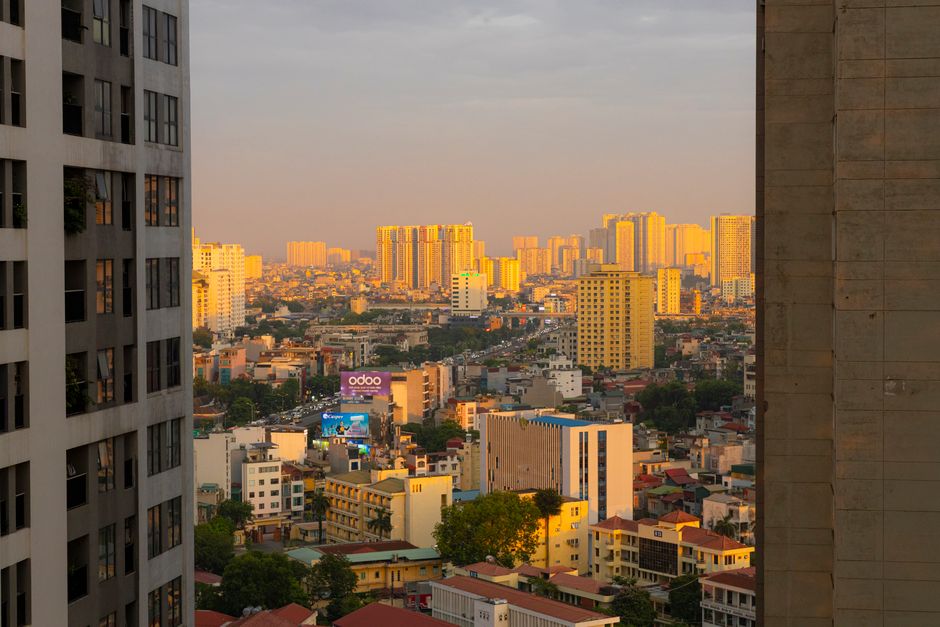
Gurgaon’s skyline has never looked more contested — cranes in Dwarka Expressway corridors, luxury towers rising along Golf Course Extension, and mid-segment projects quietly filling the gaps along Southern Peripheral Road. For anyone evaluating residential property investment Gurgaon today, the city is not a single market; it is a collection of micro-markets with genuinely different risk-reward profiles.
Understanding where you are on the capital appreciation vs. rental income spectrum matters more in 2025 than it did even three years ago, because interest rates, remote-work patterns, and new infrastructure have reshuffled the rankings considerably.
Micro-Markets That Are Delivering Capital Appreciation
Capital appreciation is strongest where supply is constrained and infrastructure is actively improving. Three zones stand out this year.
Dwarka Expressway corridor has arguably been Gurgaon’s most rewarding bet over the last 24 months. With the expressway now fully operational and the extension of the Delhi Metro’s Green Line progressing, properties in Sectors 84–95 have recorded price increases of 28–35% since early 2023, according to data tracked by ANAROCK Property Consultants, one of India’s most-cited residential research firms. Inventory launched here is being absorbed faster than it is replaced, which is textbook appreciation territory.
Golf Course Extension Road (New Gurugram, Sectors 57–65) remains the city’s luxury-appreciation story. Branded residences, ultra-premium plotted developments, and gated communities targeting C-suite buyers have pushed average ticket sizes past ₹4 crore. Because land parcels are scarce and DDJAY (Deen Dayal Jan Awas Yojana) plotted schemes have matured, resale premiums here are compounding well above inflation.
Southern Peripheral Road (SPR), particularly Sectors 68–75, is the sleeper pick. Commercial office parks by major IT occupiers are pulling in talent that, in turn, needs upscale housing within a 15-minute commute. Price per square foot has climbed roughly 18–22% year-on-year, yet SPR still trades at a discount to Golf Course Extension, leaving room for further appreciation as the precinct matures.
If capital growth is your priority, the common thread across all three zones is proximity to either metro connectivity or established employment hubs — ideally both.
Micro-Markets That Are Delivering Rental Income
Rental yield in Gurgaon has historically been modest (2.5–3.5%) compared to cities like Pune or Hyderabad, but specific pockets are now pushing that ceiling upward.
Cyber City and DLF Phase 1–5 continue to command the city’s most dependable rental demand. Multinational tenants, expatriate families, and senior corporate professionals rent here on long leases with low vacancy periods. A well-maintained 3BHK in DLF Phase 3 can yield ₹65,000–₹90,000 per month, translating to gross yields of 3.2–3.8%. Churn is low, which matters as much as the headline number.
Sohna Road (Sectors 47–50) has become a sweet spot for mid-segment rental investors. The concentration of co-working spaces and the presence of companies like Google and American Express in nearby sectors have created steady demand from young professionals who prefer renting over buying. Typical 2BHK rents have risen 14% year-on-year, and supply pipelines remain manageable enough that vacancy has not spiked.
Manesar and IMT Manesar, often overlooked by retail investors, is a manufacturing and logistics hub drawing workers from across Haryana. Rental demand here is volume-driven rather than premium-driven, but gross yields of 4–4.5% are among the highest in the Gurgaon metropolitan region. The trade-off is that capital appreciation is slower and tenant profiles are more transient.
For rental-income seekers, CREDAI’s market outlook reports provide useful benchmarks on occupancy trends and projected supply pipelines across Haryana’s key cities, including Gurgaon.
How to Decide Which Strategy Fits You
The honest answer is that most investors in 2025 are not choosing one or the other — they are stress-testing both scenarios before committing. A few practical filters:
– Holding period: If you can hold for seven-plus years, appreciation-focused zones like Dwarka Expressway make sense even if early yields are thin (often 1.8–2.2%). If you need income within 12–18 months of possession, Sohna Road or Cyber City adjacencies are safer bets.
– Ticket size: Golf Course Extension luxury plays require deep pockets and a patient exit strategy. Sohna Road and SPR offer entry points in the ₹80 lakh–₹1.5 crore range that are accessible to a wider investor base.
– RERA compliance: Always verify project registration on the Haryana RERA portal before signing anything. Delayed possession remains the single biggest destroyer of both yield and IRR in Gurgaon.
Frequently Asked Questions
Which area in Gurgaon is best for residential property investment in 2025?
There is no single best area — it depends on your goal. For capital appreciation, Dwarka Expressway and Golf Course Extension Road are leading picks. For rental income, DLF Phase 1–5 and Sohna Road offer more consistent returns with lower vacancy risk.
What rental yield can I realistically expect in Gurgaon?
Gross rental yields across most of Gurgaon sit between 2.5% and 3.8%. Manesar and IMT Manesar can push toward 4–4.5%, while luxury segments in Golf Course Extension typically yield 2–2.5% gross despite strong capital gains.
Is Dwarka Expressway a good investment in 2025?
For capital appreciation, yes. Infrastructure completion and metro connectivity have significantly reduced the risk premium that once made buyers cautious. However, rental demand is still building, so investors focused purely on yield may need to wait 2–3 more years for the precinct to fully mature.
How do I verify a project before investing in Gurgaon?
Check the project’s RERA registration number on the Haryana RERA portal, confirm the developer’s past delivery track record, and independently verify OC (Occupancy Certificate) status for completed projects. Avoid off-plan investments where land title disputes are unresolved.
Are property prices in Gurgaon likely to correct in 2025?
A broad correction appears unlikely given the demand-supply dynamics. However, over-leveraged mid-segment launches in peripheral sectors with weak social infrastructure could see price stagnation if employment growth slows. Micro-market selection, rather than a city-wide call, is the more reliable analytical frame.
What is the minimum budget needed for residential property investment in Gurgaon?
Useful entry points begin around ₹50–60 lakh for studio and compact 1BHK units in Sohna Road or Manesar. Mid-segment 2BHK investments in established sectors like 47–57 typically require ₹80 lakh–₹1.2 crore. Premium and luxury segments start at ₹2.5 crore and above.
Trusted Property Consultants Gurgaon: Vet Before You Invest
Handing your life savings to someone you met at a property expo or found through a friend-of-a-friend referral is, frankly, a leap of faith most of us cannot afford to get wrong. Gurgaon’s real estate market moves fast, prices are high, and the consultant standing between you and a good deal has an enormous amount of power. That is precisely why knowing how to identify trusted property consultants Gurgaon buyers and investors actually rely on — rather than those who simply talk a good game — is non-negotiable before you sign anything.
This guide walks you through the concrete steps to vet a property consultant, the warning signs that should make you walk away, and the positive signals that tell you you are in capable hands.
Red Flags That Should Stop You Cold
They cannot show you a RERA registration number.
Under the Real Estate (Regulation and Development) Act, 2016, any agent facilitating property transactions in India must be registered with the relevant state’s Real Estate Regulatory Authority. In Haryana, that means Haryana RERA. If a consultant hesitates, deflects, or offers excuses when you ask for their registration number, treat it as a dealbreaker — full stop.
They push urgency without substance.
Phrases like “this price is only valid today” or “three other buyers are ready” may occasionally reflect reality, but they are also classic pressure tactics used to short-circuit your due diligence. A genuine consultant will give you time to review documents, consult a lawyer, and think clearly.
Their fee structure is murky.
Legitimate consultants earn a commission, typically from the developer or seller, and they should be upfront about this. If someone is vague about how they get paid, or if they are asking for large upfront fees before any service has been delivered, that opacity is a problem.
They discourage independent legal checks.
No credible professional will tell you that hiring a property lawyer to review title documents is unnecessary or a waste of money. Any consultant who steers you away from independent verification has a reason to do so, and that reason is rarely in your favour.
Their track record is verbal-only.
Testimonials they quote verbally are easy to fabricate. Ask for written references, Google reviews tied to real names, or LinkedIn profiles of past clients willing to speak with you. If the only evidence of their success comes from their own mouth, that should give you pause.
They are unfamiliar with the micro-market.
Gurgaon is not one market — it is dozens. Sector 29 behaves differently from Dwarka Expressway or Golf Course Extension Road. A consultant who cannot speak fluently about recent transaction prices, upcoming infrastructure changes, or developer reputations in your target area is simply not equipped to advise you.
Green Lights That Signal You Can Move Forward
RERA registration is verifiable and current.
A consultant who proactively shares their RERA number and encourages you to verify it online is starting the relationship with transparency. This is table stakes — the floor, not the ceiling — but it immediately narrows the field.
They ask more questions than they answer.
The best trusted property consultants Gurgaon professionals recommend are the ones who spend the first meeting understanding your needs: your investment horizon, your risk appetite, whether you need rental yield or long-term appreciation, and what your financing situation looks like. A consultant pitching projects before they understand you is selling, not advising.
They offer comparative options and honest trade-offs.
A good consultant will show you three or four options and walk you through the genuine pros and cons of each — including the one that earns them a lower commission. If every option they present happens to be from the same developer, ask why.
They connect you with independent professionals.
A consultant worth trusting will have a network that includes property lawyers, chartered accountants familiar with real estate taxation, and home loan advisors — and they will actively encourage you to use them. According to CREDAI, India’s apex body for real estate developers, buyer awareness and professional advisory are central pillars of a healthy property transaction ecosystem.
Their communication is consistent and documented.
They follow up calls with written summaries, send you documents promptly, and do not disappear after you show interest. Responsiveness before you commit is a reliable indicator of how they will behave after.
They have local longevity.
Someone who has operated in Gurgaon’s property market for five or more years has survived market cycles, regulatory changes, and shifting developer fortunes. That experience is genuinely valuable and hard to fake.
Frequently Asked Questions
How do I verify a property consultant’s RERA registration in Haryana?
Visit the Haryana RERA portal and search for the agent using their name or registration number. All registered agents are listed publicly, and you can confirm whether their registration is active or lapsed.
What is a reasonable commission for a property consultant in Gurgaon?
Most consultants earn between 1% and 2% of the transaction value, paid by the developer or seller rather than the buyer. If a consultant is asking you — the buyer — to pay a significant upfront fee, request a detailed written breakdown before agreeing to anything.
Should I use one consultant or speak to several?
Speaking to two or three consultants before committing is sensible. It gives you a reference point for market knowledge, communication style, and the range of options available. Just be transparent with each one that you are still in the evaluation phase.
Is a consultant with a big agency always safer than an independent one?
Not necessarily. Brand recognition provides some accountability, but individual conduct matters more. Evaluate the specific person you will be working with — their experience, their references, and how they communicate — not just the logo on their business card.
What documents should a consultant help me review before purchase?
At minimum: the title deed, encumbrance certificate, building approvals, RERA project registration, and the draft sale agreement. A trustworthy consultant will walk you through each one and recommend a lawyer for final verification.
Can a consultant represent both buyer and seller in the same deal?
Technically yes, but this creates a conflict of interest. If your consultant is also working for the developer or seller, ask how they will ensure your interests are protected. A written disclosure of all parties they represent is a reasonable thing to request.
Real Estate Advisory Services: Why You Need One
Buying property feels straightforward until it isn’t. The listing looks perfect, the open house goes smoothly, and then — somewhere between the offer, the inspection, and the closing table — things get complicated fast. That’s the moment most buyers wish they had invested in professional real estate advisory services from the start.
An advisor isn’t the same as a traditional buyer’s agent who simply shows you homes and submits paperwork. A real estate advisor takes a consultative approach: they analyze your financial situation, assess market conditions, stress-test your assumptions, and help you make a decision that holds up years after moving day.
What a Real Estate Advisor Actually Does
The day-to-day work of a real estate advisor covers far more ground than most buyers expect.
Market analysis and pricing strategy. Advisors don’t just pull comparable sales — they interpret them. They’ll tell you why a house priced at $650,000 in a softening market is likely to close at $620,000, and they’ll back that with data rather than gut feel. According to the National Association of Realtors, buyers who work with knowledgeable professionals consistently report higher satisfaction with their purchase price outcomes.
Due diligence coordination. A good advisor orchestrates the inspection process, flags red flags before you’re legally committed, and knows which issues are deal-breakers versus negotiating chips. They’re not just reading the inspection report — they’re reading between the lines.
Contract and negotiation expertise. Purchase agreements are dense documents. An advisor reviews contingency language, earnest money terms, and seller concession structures to protect you. They’ll push back on clauses that look standard but quietly shift risk onto the buyer.
Network access. Established advisors bring a vetted network of lenders, inspectors, attorneys, and contractors. This isn’t a minor perk. A trusted inspector who catches a foundation issue saves you tens of thousands of dollars. A lender who closes on time saves your deal.
Long-term investment perspective. Rather than asking “do you like this house?” an advisor asks “will this house serve your goals in five, ten, or twenty years?” They factor in neighborhood trajectory, resale liquidity, and how the property fits your broader financial picture.
What Separates an Advisor from a Standard Agent
Traditional buyer’s agents earn a commission when a transaction closes. That structure, while common, creates an incentive to close deals rather than to scrutinize them. A real estate advisor — whether fee-based or commission-based — is positioned explicitly as your advocate, not a transaction facilitator. The distinction matters especially in competitive markets where speed pressure can override sound judgment.
Why Buying Without One Costs You More
The most common objection to hiring an advisor is cost. That concern deserves a direct answer: in most cases, buyers who skip professional real estate advisory services lose far more than they save.
Overpaying on purchase price. Without a skilled negotiator in your corner, sellers and their agents set the terms. Buyers routinely pay 2–5% above what a well-represented buyer would in the same transaction. On a $500,000 home, that’s $10,000–$25,000 left on the table.
Missed inspection issues. Unrepresented buyers often waive inspections to compete, or they don’t know which inspection findings warrant renegotiation. The Consumer Financial Protection Bureau notes that unexpected home repair costs are among the leading financial stressors for first-time buyers in the years following purchase.
Contract missteps. Poorly structured contingencies can leave a buyer unable to recover their earnest money if a deal falls through for legitimate reasons. An advisor knows how to write airtight contingencies that protect your deposit without making your offer look weak.
Emotional decision-making. Buying a home is personal. That’s not a flaw — it’s human. But emotion without a counterbalance leads to overbidding on homes you’ve fallen in love with, overlooking serious problems because the kitchen is beautiful, or panic-buying in a rising market without a clear-headed assessment of value. An advisor provides that counterbalance.
Post-purchase regret. Studies consistently show that buyers who felt rushed or under-advised are more likely to report dissatisfaction with their purchase. An advisor slows things down just enough to make sure you’re confident — not just committed.
The fee structure for real estate advisory services varies. Some advisors charge a flat fee, others work on commission, and some blend both. In many transactions, the seller covers the buyer’s advisor’s compensation through the sale proceeds, meaning the buyer receives professional guidance at no direct out-of-pocket cost. Even when there is a direct fee, the math almost always favors the investment.
Frequently Asked Questions
What is the difference between a real estate advisor and a buyer’s agent?
A buyer’s agent primarily helps you find and purchase a property, earning a commission at closing. A real estate advisor takes a broader consultative role — analyzing your financial goals, scrutinizing deals critically, and advocating for your long-term interests rather than simply facilitating a transaction.
How much do real estate advisory services typically cost?
Costs vary widely. Some advisors charge flat project fees ranging from a few hundred to several thousand dollars. Others work on commission, which in many markets is paid by the seller. Always clarify the fee structure upfront so there are no surprises at closing.
Is a real estate advisor worth it for a straightforward purchase?
Yes — straightforward purchases can become complicated quickly. Even an uncomplicated transaction involves contract language, inspection findings, and financing contingencies that benefit from professional review. The risk of skipping guidance rarely justifies the savings.
When should I engage a real estate advisor in the buying process?
As early as possible — ideally before you start actively touring properties. An advisor shapes your search criteria, helps you understand true market value in your target area, and ensures your financing is structured correctly before you fall in love with a home.
Can a real estate advisor help with investment properties, not just primary homes?
Absolutely. Real estate advisory services are especially valuable for investment purchases, where return on investment, rental income projections, and exit strategy matter as much as the property itself.
What should I look for when choosing a real estate advisor?
Look for demonstrated local market knowledge, a clear explanation of how they’re compensated, verifiable client references, and a communication style that prioritizes your questions over their schedule. An advisor who listens carefully before speaking is almost always more valuable than one who talks fast.
How to Buy Property in India: 11 Due Diligence Steps

Purchasing real estate is one of the largest financial decisions most people ever make, and when you set out to learn how to buy property in India, the complexity can feel overwhelming. Opaque title records, fragmented local regulations, and high-pressure sales tactics are genuine hazards — not just urban legends. The good news is that a disciplined due diligence process dramatically reduces your risk. Work through every step below before handing over a rupee.
The Legal and Title Checks You Cannot Skip
1. Verify the title chain for at least 30 years.
Request all original sale deeds, gift deeds, or inheritance documents going back three decades. A clean, unbroken chain confirms the seller has the legal right to sell. Any gap is a red flag worth investigating with a property lawyer.
2. Get an encumbrance certificate (EC).
Obtain an EC from the sub-registrar’s office covering the same 30-year window. The EC lists every mortgage, lien, and charge registered against the property. If the seller claims there is no loan on the property but the EC says otherwise, walk away or insist on full loan closure before proceeding.
3. Confirm land-use and zoning classification.
Check the local development authority’s master plan to confirm the land is classified for the purpose you intend — residential, commercial, or agricultural conversion. Building a home on land zoned for agriculture can lead to demolition orders and zero compensation.
4. Inspect approved building plans.
For under-construction or already-built structures, ask for the approved building plan sanctioned by the municipal corporation or panchayat. Compare what is on paper with what is on the ground. Unauthorised floors or extensions may attract penalties or demolition.
5. Check RERA registration for new projects.
If you are buying from a developer, verify the project’s registration on your state’s Real Estate Regulatory Authority portal. RERA-registered projects are legally obligated to disclose timelines, approvals, and escrow accounts — giving you significant consumer protection that unregistered projects do not.
6. Review property tax receipts.
Ask for the last three to five years of paid property tax receipts. Unpaid dues become your liability the moment ownership transfers. Also confirm the name on the tax records matches the seller’s identity documents.
7. Confirm there are no pending litigation matters.
Have a lawyer run searches at the local civil court and the high court to check whether the property is party to any lawsuit, partition dispute, or insolvency proceedings. Litigation-encumbered properties can freeze your ownership rights for years.
Financial, Physical, and Procedural Checks
8. Conduct an independent market valuation.
Do not rely solely on the builder’s pricing or a broker’s word. Hire a certified valuer to assess fair market value independently. This protects you from overpaying and also determines the stamp duty baseline, as the government’s circle rate sets the minimum taxable value for registration.
9. Inspect the physical condition thoroughly.
For resale properties, hire a qualified structural engineer to check for dampness, foundation integrity, and electrical wiring quality. Cosmetic renovations often hide serious structural problems. The cost of a professional inspection — typically ₹5,000 to ₹15,000 — is trivial compared to repair bills.
10. Understand all costs before you commit.
The sticker price is never the final price. Budget for stamp duty (typically 5–7% of property value depending on the state), registration fees, GST on under-construction units, broker commissions, home loan processing fees, and society transfer charges. According to guidance published by the Reserve Bank of India, borrowers should also account for property insurance when planning home loan repayments.
11. Draft a robust sale agreement before paying any advance.
Before paying a token or booking amount, have a lawyer draft or review the sale agreement. It must specify the total consideration, payment schedule, possession date, penalty clauses for delay, and what happens if approvals are denied. Never rely on verbal assurances — what is not in the agreement does not exist legally.
Knowing how to buy property in India is ultimately about asking the right questions at each stage. Sellers and developers rarely volunteer uncomfortable information, so your due diligence process is your primary defence.
Take your time. A genuinely good property will still be available after a thorough two-to-four week verification period. If a seller insists you must decide within 24 hours, that urgency itself is a warning sign worth heeding.
Frequently Asked Questions
How long does the property buying process take in India?
From shortlisting to registration, expect the process to take between 60 and 120 days if no title disputes arise. Complex cases involving inherited property or NRI sellers can take longer due to additional documentation requirements.
Is it safe to buy under-construction property in India?
It can be, provided the project is RERA-registered and the developer has a track record of delivering on time. Always check that construction funds are held in an escrow account as mandated by RERA, which prevents diversion of buyer payments.
What is circle rate and why does it matter?
Circle rate (also called guidance value or ready reckoner rate) is the minimum property value set by state governments for stamp duty calculation. Even if you negotiate a lower purchase price, stamp duty is calculated on whichever is higher — the actual price or the circle rate.
Can an NRI buy property in India?
Resident Indians face no restrictions, and Non-Resident Indians (NRIs) can purchase residential and commercial property freely. However, NRIs cannot buy agricultural land, farmhouses, or plantation property without special RBI approval.
Do I need a lawyer or can I rely on the broker?
You should always engage an independent property lawyer. A broker’s income depends on the transaction closing; a lawyer’s duty is solely to your interests. Legal fees for a standard property transaction typically range from ₹10,000 to ₹30,000 — money well spent.
What happens if the seller has an outstanding home loan on the property?
The existing loan must be fully closed and the original documents retrieved from the lender before registration. One common approach is a tripartite agreement among the buyer, seller, and the lender, where part of the purchase price is paid directly to the bank to discharge the mortgage.
Residential Property Investment for Beginners: Step-by-Step
Buying your first investment property is one of the most significant financial decisions you will ever make. The gap between “I want to invest in property” and actually holding a set of keys can feel enormous — filled with mortgage jargon, competing advice, and the nagging fear of making an expensive mistake. The good news is that residential property investment for beginners becomes far less intimidating once you break it into a logical sequence of steps. This roadmap does exactly that.
Setting Your Budget and Financial Foundations
Before you browse a single listing, you need an honest picture of what you can actually afford — not what you hope you can afford.
Work out your borrowing capacity first. Speak to a mortgage broker or your bank to get an Agreement in Principle (AIP). Lenders assess investment mortgages differently from residential ones: they typically require a 20–25% deposit, and they stress-test rental income to ensure it covers 125–145% of the monthly mortgage payment. Knowing your ceiling early stops you falling in love with a property that was never within reach.
Build your full cost picture. Purchase price is just the headline number. Stack up stamp duty (or its local equivalent), legal fees, survey costs, letting agent fees, landlord insurance, and an emergency maintenance reserve. A common rule of thumb is to budget an additional 8–10% of the purchase price for these upfront costs. Running short at completion is a stressful and avoidable problem.
Define your return targets. Two metrics matter most at this stage: gross rental yield (annual rent divided by purchase price, expressed as a percentage) and cash flow (monthly rent minus all monthly outgoings). A gross yield below 4% in a high-cost city may still work if capital growth is your primary goal, but if you need the investment to pay for itself from day one, target 6% or higher. The UK Government’s guidance on property income tax is worth reading at this stage, because tax treatment directly affects your net return.
Stress-test every assumption. What happens if the property sits vacant for two months? What if interest rates rise by 1%? Investors who skip this exercise are often the ones who sell under pressure two years later.
Finding, Evaluating, and Securing the Right Property
With your finances organised, you can approach the market methodically rather than emotionally.
Choose your strategy before you choose a location. Are you targeting young professionals who want a low-maintenance city flat? Families who need good school catchment areas? Students near a university? Each tenant type has different priorities, and those priorities should dictate where you buy and what type of property you buy. Trying to find the perfect property without a strategy is like shopping without a list.
Research locations with data, not instinct. Look for areas where employment is growing, transport links are improving, or regeneration money is being spent. Rental demand in these areas tends to be more resilient, and void periods shorter. Check average asking rents on platforms like Rightmove’s rental market data to validate whether asking rents in a target area are realistic.
Carry out thorough due diligence on every shortlisted property. Commission a RICS-accredited surveyor rather than relying on the lender’s basic valuation. A HomeBuyer Report or full structural survey will surface issues — subsidence, damp, roof wear — that can turn a promising investment into a money pit. Paying £400–£800 for a survey is cheap insurance against a five-figure repair bill.
Understand the negotiation landscape. In a buyer’s market, 5–10% below asking price is often achievable, especially on properties that have been sitting unsold for more than eight weeks. In a competitive market, moving quickly with a clean offer (no chain, finance agreed) is often worth more than a slightly higher bid from a chain buyer.
Manage the legal process actively. Appoint a solicitor experienced in buy-to-let conveyancing. Chase your solicitor weekly rather than waiting for them to come to you — transactions that drift are transactions that fall through. Confirm the completion date in writing as early as possible, and have your deposit funds ready to transfer immediately when contracts exchange.
Prepare for tenancy before you complete. While conveyancing is underway, arrange landlord insurance, research local letting agents, and draft a compliance checklist covering gas safety certificates, electrical installation condition reports (EICRs), Energy Performance Certificates (EPCs), and deposit protection. Being operationally ready on completion day means your property can generate income within weeks, not months.
The journey from first viewing to key handover typically takes three to five months. Patience and preparation — not luck — are what separate investors who build long-term portfolios from those who treat residential property investment for beginners as a one-time gamble.
Frequently Asked Questions
How much deposit do I need for a residential investment property?
Most buy-to-let mortgage lenders require a minimum deposit of 20–25% of the property’s purchase price. A larger deposit — say 30–35% — typically unlocks better interest rates, which improves your monthly cash flow from day one.
Is a limited company better than buying in my personal name?
This depends heavily on your income tax band and longer-term portfolio plans. Higher-rate taxpayers often benefit from purchasing through a limited company because mortgage interest is fully deductible. However, company mortgages can carry higher rates and additional admin costs. Speak to a qualified accountant before making this decision.
How do I calculate rental yield on a property?
Divide the annual rental income by the property’s purchase price, then multiply by 100. For example, a property bought for £200,000 generating £10,000 per year in rent has a gross yield of 5%. Always calculate net yield too, subtracting running costs from the income figure before dividing.
What insurance do I need as a landlord?
At a minimum you need buildings insurance and landlord liability insurance. Contents insurance is advisable if the property is furnished. Some landlords also take out rent guarantee insurance, which covers lost rent if a tenant defaults — particularly useful during the early years of building your portfolio.
How long does the purchase process typically take?
From offer acceptance to completion, expect three to five months for a straightforward buy-to-let purchase. Complex chains, slow solicitors, or mortgage complications can extend this. Keeping communication flowing with your solicitor and mortgage broker is the single most effective way to stay on schedule.
Can I manage the property myself instead of using a letting agent?
Yes, but self-management requires time, local knowledge, and confidence handling legal compliance, maintenance calls, and occasionally difficult conversations with tenants. Full property management through an agent typically costs 10–15% of monthly rent but buys you peace of mind and removes day-to-day involvement, which many first-time investors find invaluable.